Off-plan versus ready: a staged cash requirement table (2026)
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents+
Dubai Land Department's fee schedule, verified 20 September 2026, assigns 2% of the sale value to the seller and 2% to the purchaser, so the official split on a hypothetical AED 2 million home is AED 40,000 each before the contract reallocates anything. The larger difference between off-plan and ready property is timing: off-plan converts cash into a provisional Oqood record and staged obligations, while ready property concentrates the balance around title transfer and can move into leasing once ownership and Ejari requirements are met.
The comparison turns on when cash becomes usable again
Off-plan spreads the purchase price but ties each payment to a contract and a future asset; ready property concentrates cash at transfer but produces title to an existing home. That is the practical distinction for an international buyer managing liquidity across currencies, bank accounts and dates.
DLD's initial-sale service says the developer must register the signed SPA in the provisional register within 90 days. Its completed-sale service instead ends with an electronic title deed and map. Those are different cash and evidence milestones, even when the purchase price is identical.
Oqood, escrow and title deed are three different records
Oqood records the off-plan contract, escrow receives project money, and the title deed records completed ownership. Treating those terms as interchangeable makes the cash calendar look shorter than it is.
- Oqood is DLD's portal for a developer to register an off-plan sale in the provisional register. The output is a provisional registration e-certificate. It records the contract while the unit is not yet on the completed Real Estate Register.
- Escrow is the project's bank account into which buyer and project-financier payments are deposited. DLD's official escrow FAQ says the regime applies to Dubai developers that sell units off-plan and receive those payments. It regulates how project money is held and used; it does not turn the provisional certificate into a completed title.
- Title deed is DLD's electronic ownership certificate for the completed property. DLD's completion-of-provisional-procedures service issues it once the relevant parties have met their contractual obligations and the provisional procedures are completed.
This sequence explains the liquidity difference. An off-plan buyer can have a registered interest and money in escrow without yet holding a completed home that can support occupation or a tenancy. A ready buyer reaches title at the transfer event.
Worked calendar one: an illustrative off-plan purchase
On the illustrative plan below, AED 800,000 leaves before handover and AED 1,200,520 is due at handover and title completion. The plan is deliberately simple: an AED 2 million price, with 10% at booking, 30% during construction and 60% at handover. Those percentages are scenario inputs, not a statement about the wider market.
The AED 40,020 provisional-registration line uses DLD's official purchaser share of 2% on AED 2 million, plus AED 10 knowledge and AED 10 innovation charges. DLD also lists an AED 1,000 developer self-registration fee for the provisional sale. It is not added to the buyer's total because the official page places it on developer self-registration; check the SPA for any contractual administration charge.
The handover fee line uses DLD's current AED 250 title-deed fee, AED 250 unit-map fee, AED 10 knowledge charge and AED 10 innovation charge. If the SPA makes the buyer fund the seller's official 2% share as well, the example needs another AED 40,000. That is a contract allocation, not DLD's stated default split.
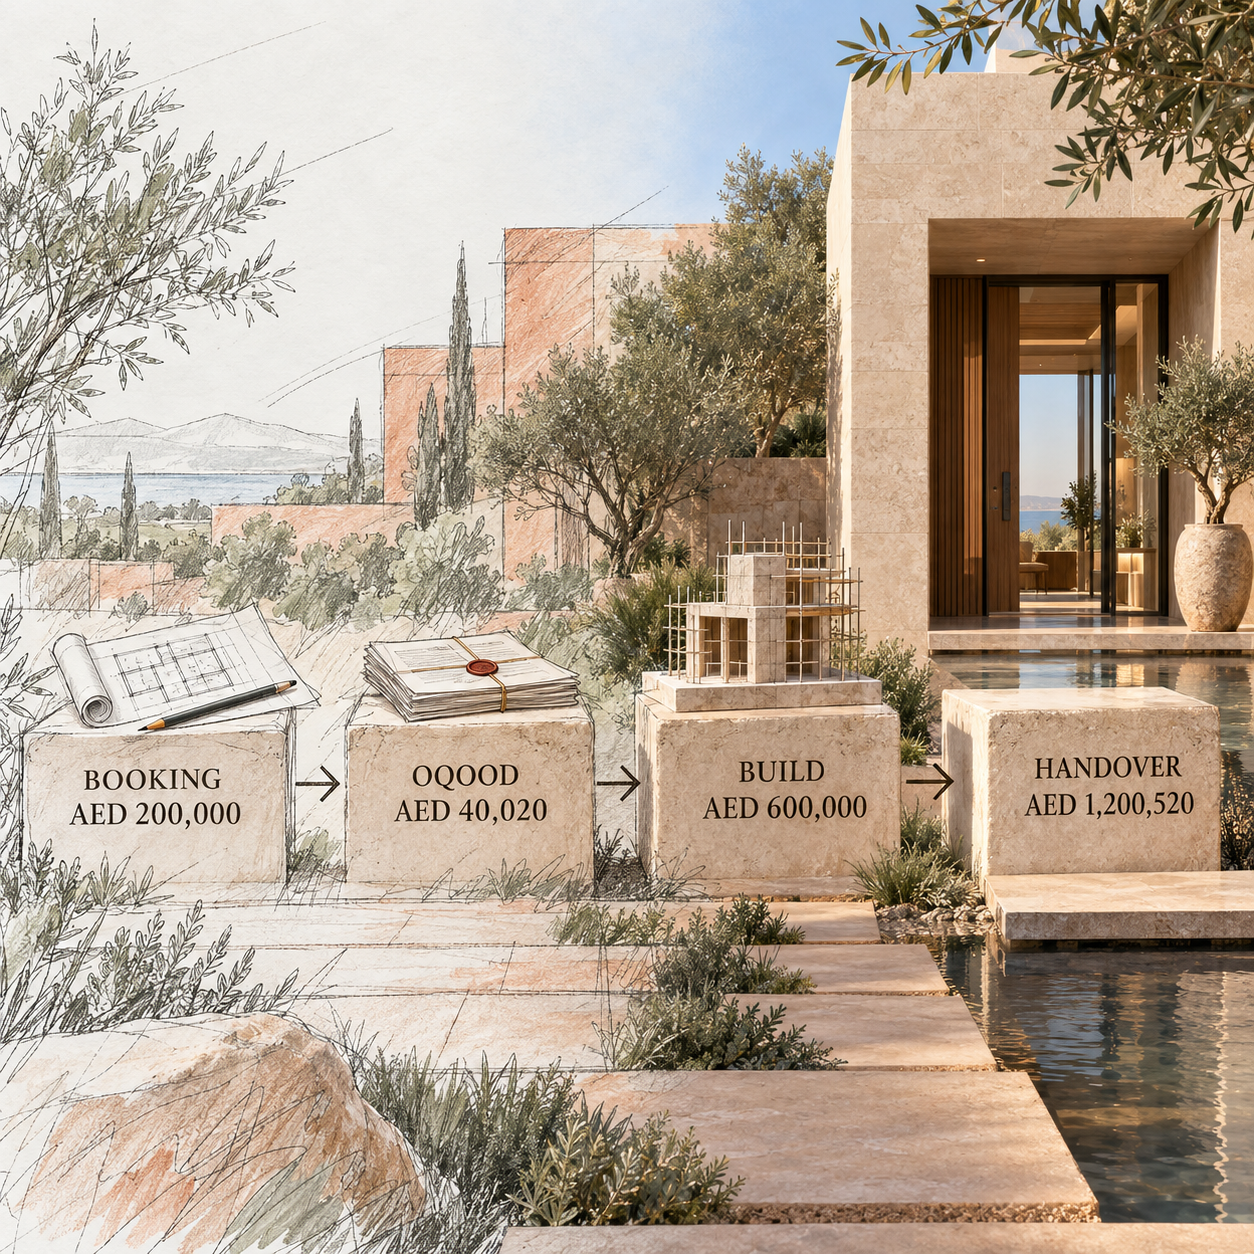
This cash curve fits a buyer whose liquidity arrives in known stages and whose use date sits after handover. It is a weaker timing match for a buyer who needs the property to produce rent while construction continues.
Worked calendar two: an illustrative ready purchase
The ready example requires AED 1,844,720 at transfer after an illustrative AED 200,000 reservation has already been credited to the price. It uses the same AED 2 million price and an all-cash purchase so the transfer mechanics remain visible without assuming a bank's lending decision.
The AED 44,720 fee line is the buyer's official 2% share of AED 40,000, the AED 4,000 service-partner fee plus 5% VAT, the AED 250 title-deed fee, the AED 250 apartment or villa map fee, and AED 10 each for knowledge and innovation. The Federal Tax Authority's VAT page shows the 5% standard rate. If Form F assigns the seller's 2% share to the buyer, add AED 40,000 to this model.
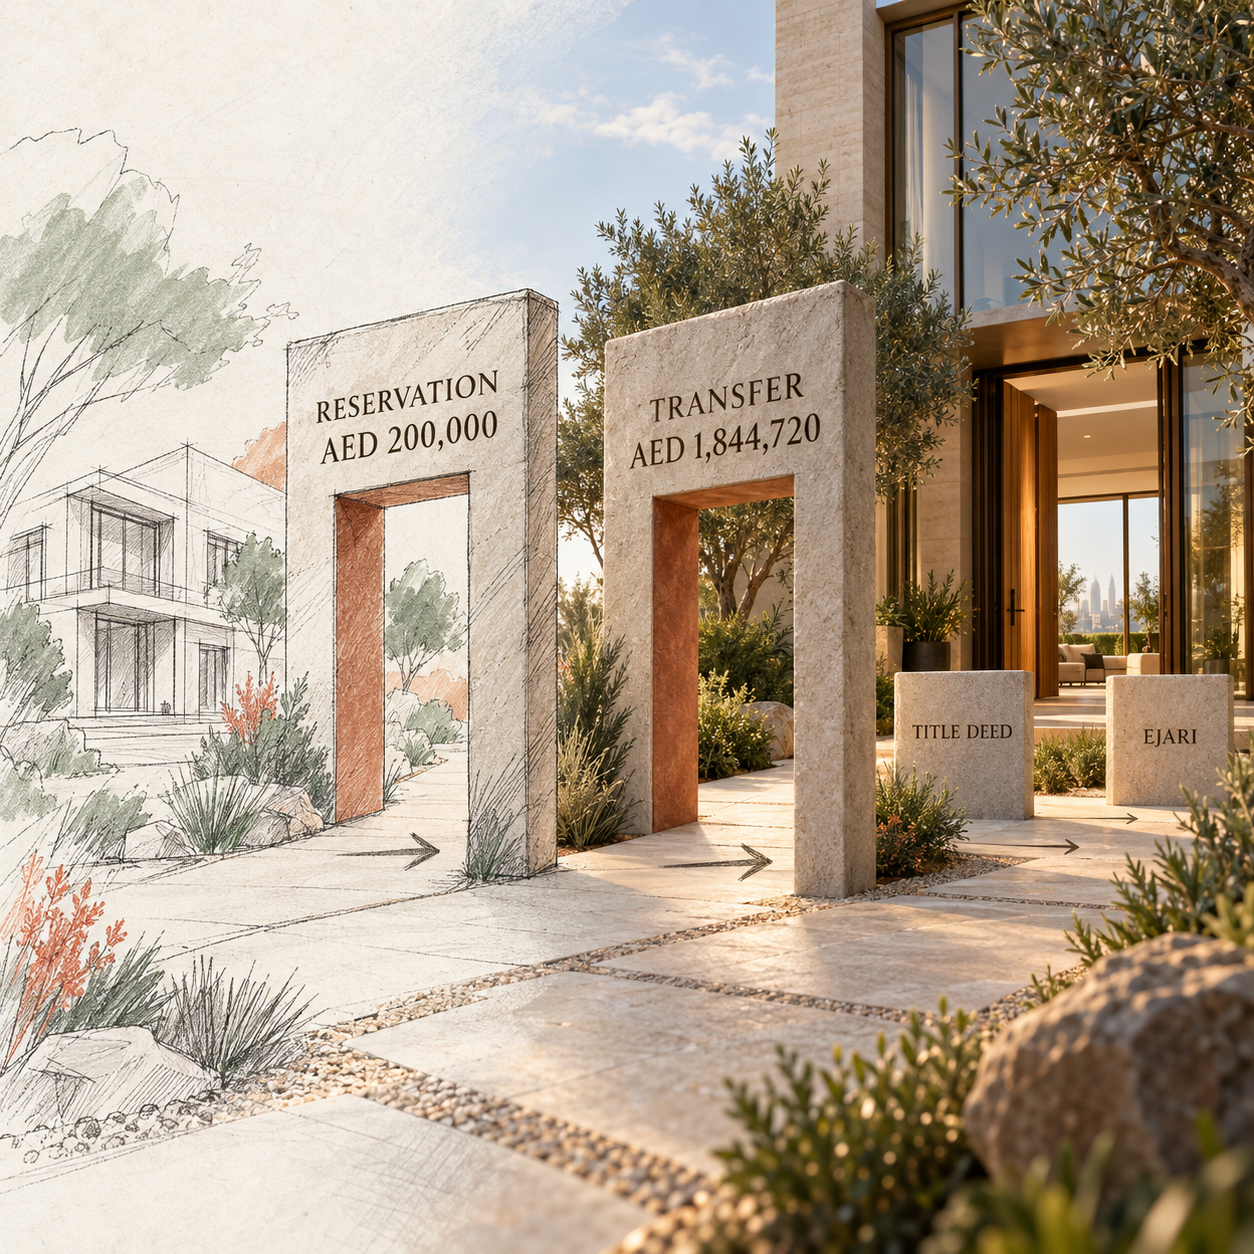
For the detailed sequence from Form F to cleared rent, use the reviewed ready-property cash-flow calendar. This comparison keeps the focus on how its concentrated transfer event differs from the off-plan stages.
Mortgage timing changes the cash curve
A mortgage reduces purchase-price cash only after the lender approves the borrower, the property and the drawdown conditions. The regulatory LTV is a maximum, not an entitlement to that loan amount.
As of 20 September 2026, the CBUAE mortgage-loans regulation sets a 50% maximum LTV for all off-plan purchases. It also says the buyer's equity must be used before construction-stage loan money and that lender payments must follow completion milestones confirmed by the lender or an independent professional.
For completed property, the same rulebook caps an expatriate first-house loan at 80% when the property is below AED 5 million and 70% when it is above AED 5 million. The cap for an expatriate second or subsequent house, or an investment property, is 60% regardless of value. A bank can apply a lower LTV after its income, debt and valuation checks.
DLD charges 0.25% of the mortgage value to register the mortgage, as shown on its mortgage-registration service. That fee belongs in the buyer's transfer or construction-funding calendar only after the actual loan amount and registration route are known.
Service charges and rent begin on different evidence
Service charges become a modelled outflow when a specific project, year and ownership period are known; rent becomes a receipt only after a lease exists and payment clears. Neither line should be filled with a generic percentage.
RERA's Service Charge Index displays approved charges by project, use and year through Mollak, the system for jointly owned property charges. For ready property, pull the current project-year amount before transfer and place it from the ownership date in the completion statement. For off-plan, add the approved amount when the handover and management documents establish the first payable period.
DLD's Ejari registration service requires the landlord to be the owner or an authorised representative. As checked on 20 September 2026, the official total is AED 177.75 through Dubai REST or the DLD website and AED 220 through a trustee centre. Those are tenancy-registration charges, not evidence that rent has already cleared.
Best fit depends on the liquidity profile
The strongest match is the route whose cash dates line up with the buyer's real funding dates, use date and tolerance for capital being committed before rent can start.
The table is routing, not a verdict on value. Replace the hypothetical price and payment plan with the actual SPA or Form F, then rebuild the calendar from documentary cash dates.
What does off-plan property mean in Dubai?
As checked on 20 September 2026, DLD treats it as a unit sold before completion and registered by the developer in the provisional register through Oqood. The buyer receives a provisional registration certificate rather than the completed property's title deed.
Is it worth buying off-plan in Dubai?
There is no universal answer. On 20 September 2026, the useful test is whether the signed payment schedule, future handover date, 50% off-plan mortgage ceiling and period before rent match the buyer's own liquidity calendar.
Can I sell an off-plan property before completion?
The route depends on the SPA, the developer's transfer process and the provisional registration record. As of 20 September 2026, verify the specific assignment or resale conditions with the developer, DLD or a licensed agent before treating an off-plan contract as readily saleable.
Can I get a loan for an off-plan property in Dubai?
Yes, subject to lender and project approval. The CBUAE rulebook checked on 20 September 2026 caps off-plan mortgage LTV at 50% and requires owner equity to be used before construction-stage loan money.
Which route can start rent sooner?
A vacant ready property has the earlier route because title transfer can be followed by a tenancy contract and Ejari. An off-plan unit must first complete construction, handover and the ownership steps; the exact rent date then depends on securing a tenant and receiving cleared payment.
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.