Golden Visa property file: valuation and ownership evidence (2026)
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents+
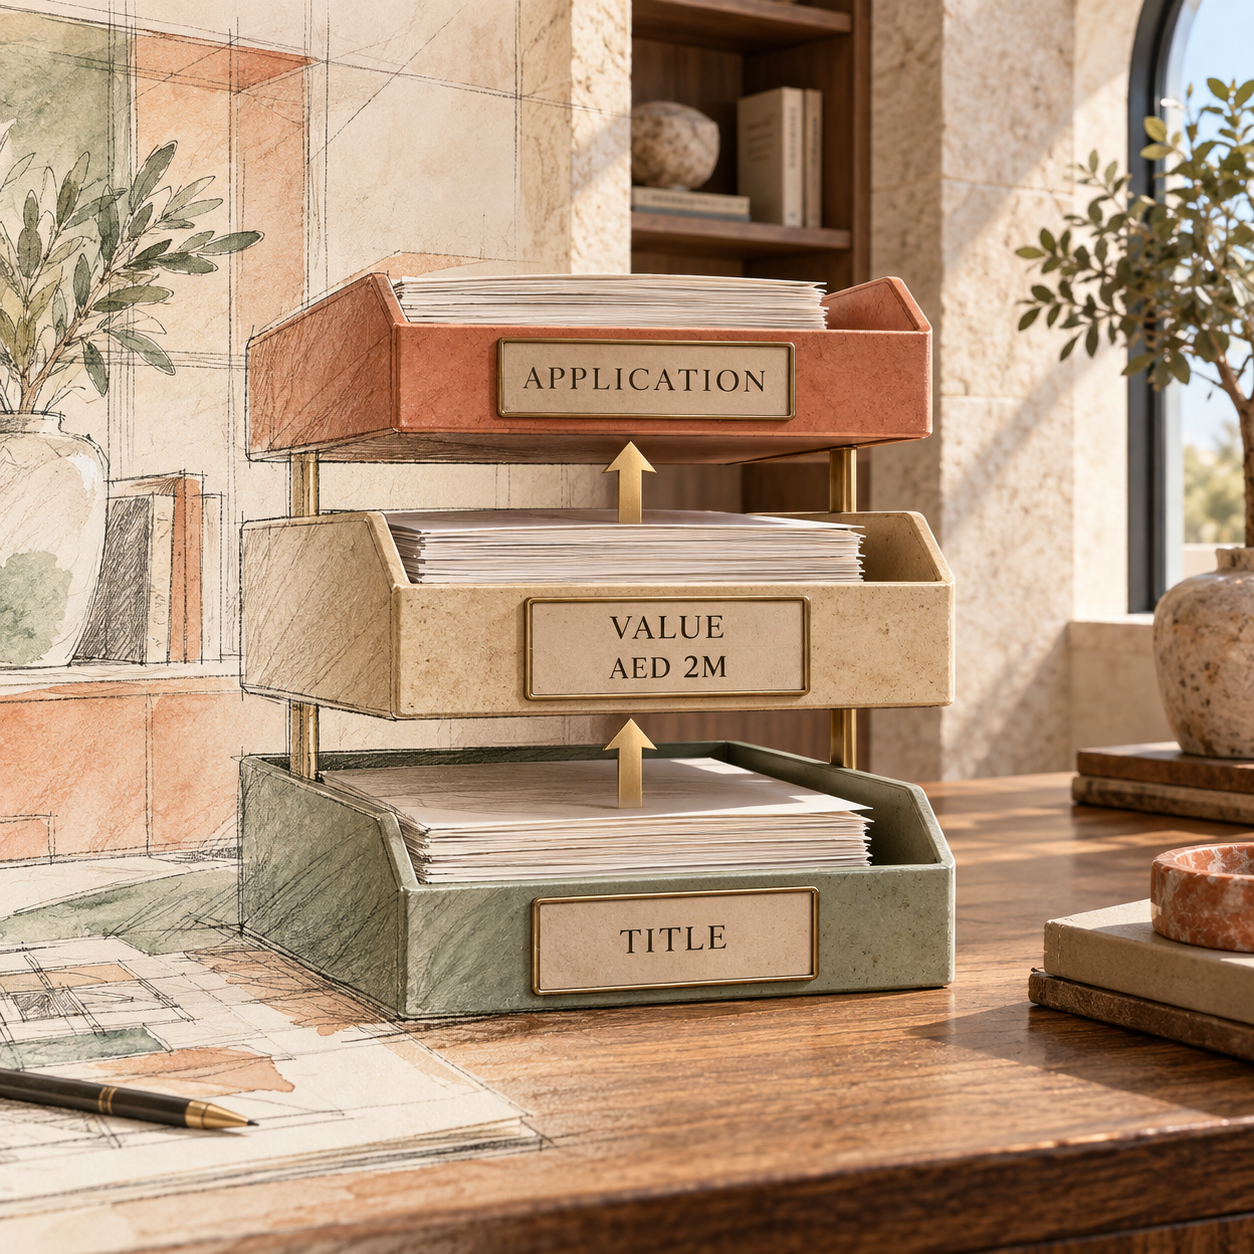
As of 21 September 2026, Dubai's property route uses an AED 2 million qualifying line, and GDRFA says a joint owner's own share must reach that amount. The evidence file therefore has three separate jobs: prove registered ownership, certify the property or share value, and complete the identity and residence application record.
The evidence file has three separate jobs
The title record answers who owns the asset, the valuation record answers what value the authority can rely on, and the residence file identifies the applicant. These are related records, but they are not interchangeable.
This boundary matters because a purchase contract, asking price or portal estimate is not named as the value certificate on the current GDRFA page. Equally, a valuation certificate does not replace the title record that DLD lists for the investor service.
The broader Dubai property investor visa guide covers the residency routes. This companion stays with the documents that connect a property record to the Golden Visa file.
A title deed proves registration, not every value question
DLD's current Golden Visa investor page requires an e-Certificate of Title or title deed. That is the starting ownership record for a completed, registered Dubai property.
The same page describes the service as available where the property purchase value was at least AED 2 million at the time of purchase. Its service terms say the value can sit across one or more properties, wholly owned under the applicant's name. GDRFA adds a separate current requirement: the property value must be certified by a DLD property status statement certificate.
Read together, the official pages draw a practical line:
- Title or e-Certificate: identifies the registered owner and property.
- Property status statement: provides the DLD-certified status and value evidence named by GDRFA.
- Valuation certificate: may be accepted through an office licensed by DLD, according to GDRFA.
DLD also operates ownership-statement and detailed-property-report services. Those records can show ownership, property and mortgage details, but DLD's current Golden Visa required-document list does not name either one as a universal extra document. The file should follow the document requested for the selected application channel, not collect every DLD certificate by default.
Current value needs its own official route
GDRFA's current page says the property value must be certified by a property status statement issued by DLD. It also says a property valuation certificate may be accepted through offices licensed by DLD. That wording creates two official evidence routes, but it does not say that every file must contain both.
Where a valuation certificate is requested, DLD's general Property Valuation service publishes the following residential route as of 21 September 2026:
These are the fees and inputs for DLD's general property valuation service, not an automatic extra charge for every Golden Visa applicant. If the application channel accepts the DLD property status statement, the official GDRFA wording does not establish that a second valuation certificate is always necessary.
DLD also publishes a live list of RERA-accredited valuation companies. RERA is the Real Estate Regulatory Agency within DLD. The list is the official place to check whether a valuation company is accredited in Dubai at the time the report is ordered.
An asking price and a certified value serve different purposes. The Dubai property valuation guide explains how market evidence is assembled, while this residence file relies on the certificate or statement the authority accepts.
Joint ownership is tested at share level
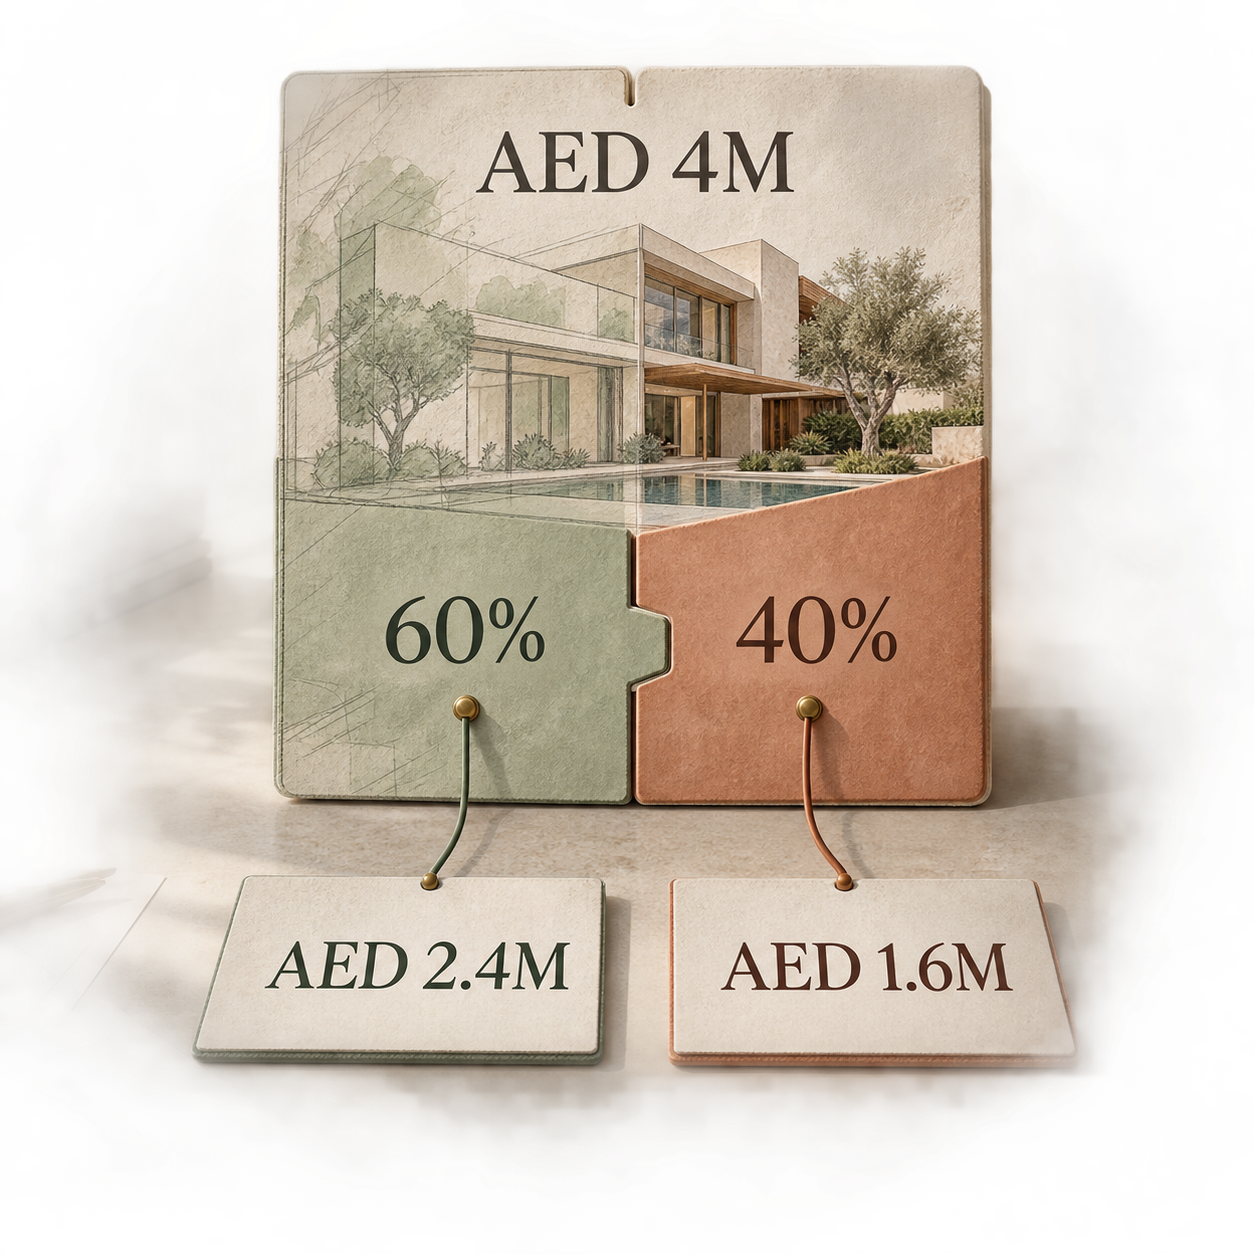
GDRFA's current rule is direct: if ownership is a share in a joint property, the value of that share must not be less than AED 2 million. The whole property's value is therefore not the applicant's evidence unless the applicant owns the whole property.
Consider a hypothetical property with a certified value of AED 4 million and registered shares of 60% and 40%:
The example is arithmetic, not a property valuation. The actual file needs the registered ownership split and the certified value evidence accepted by the authority.
The current GDRFA page does not publish a separate spouse-aggregation exception in this rule. A married couple holding one property should therefore treat combined-share treatment as an open verification step with DLD or the accredited submission centre, rather than assume that marriage changes the stated share test.
Mortgaged property adds bank evidence
DLD says a mortgaged property can be used, but the file must include a bank no-objection letter. The service terms say that letter should state the paid amount and the outstanding balance, while the service description says AED 2 million paid must be shown as proof.
That makes the bank letter a separate evidence layer. It does not replace the title record or the authority's value certificate. A clean mortgage file therefore keeps together:
- the e-Certificate of Title or title deed;
- the certified property-value record requested by the channel;
- the bank no-objection letter;
- the paid amount and balance stated by the bank.
The lender, DLD record and applicant identity should use matching property and owner details. If the bank letter is being prepared for this purpose, the current wording can be checked against DLD's service page before submission because the paid-amount formulation may affect whether the record answers the authority's question.
The residence application file is a separate checklist
DLD's current Golden Visa investor service lists five core application documents: a passport, an e-Certificate of Title or title deed, a personal photo, a UAE ID if the applicant has one, and a copy of the current residence permit if the applicant has one.
The same DLD page says the applicant must be inside the UAE and must attend personally. It lists accredited application centres and says the residence permit is sent by email after the file, payment and medical examination steps are completed.
Match the owner identity
Check that the passport name and the DLD ownership record identify the same applicant. Add the UAE ID and current residence permit only where they exist.
Choose the accepted value record
Confirm whether the selected channel wants the DLD property status statement or will accept a valuation certificate from a DLD-licensed office. Do not treat an asking price as either document.
Add structure-specific evidence
For joint ownership, make the registered share visible. For a mortgage, include the bank no-objection letter with the paid amount and balance.
Recheck the service scope
DLD's investor service and GDRFA's permit page describe different parts of the route. Check the selected centre's current document names before paying for an extra certificate.
DLD publishes a total of AED 9,884.75 for its 10-year investor service as of 21 September 2026. The page breaks that into AED 700 for the medical examination, AED 1,153 for a 10-year Emirates ID, AED 2,856.75 for residence confirmation, AED 4,020 in DLD fees and AED 1,155 in administrative fees. Its published service time is 7 to 10 business days.
Those service amounts are separate from the AED 4,000 residential valuation fee where a valuation certificate is actually ordered. The two totals should not be combined until the selected application channel confirms that the valuation service is needed.
Sources and date boundary
This evidence map was checked on 21 September 2026 against the DLD Golden Visa investor service, the GDRFA investor Golden Residence service, DLD's Property Valuation service and the UAE Government Golden Visa overview. The UAE Government page was updated on 28 July 2026 and states the AED 2 million minimum capital line for real-estate investors.
The DLD and GDRFA pages do not use identical descriptions for every value document. That is why the file map distinguishes a stated rule from an open channel-confirmation step.
Is a title deed enough for a Dubai property Golden Visa?
The title deed or e-Certificate proves registered ownership, but GDRFA separately says the property value must be certified by a DLD property status statement. It also says a valuation certificate through a DLD-licensed office may be accepted, as checked on 21 September 2026.
Does the total property value count for a joint owner?
GDRFA says the applicant's share in a joint property must itself be worth at least AED 2 million. The whole-property value and the registered ownership percentage are therefore both needed to understand the applicant's share value.
Can a mortgaged Dubai property be used in the Golden Visa file?
DLD says a mortgaged property is acceptable and requires a bank no-objection letter showing the paid amount and balance. Its service description also refers to AED 2 million paid as proof, as of 21 September 2026.
Does DLD currently list Oqood as the required ownership document?
The current DLD Golden Visa service page lists an e-Certificate of Title or title deed, not Oqood. An off-plan owner should confirm the accepted substitute with DLD or the selected accredited centre for that specific file.
How long does the DLD Golden Visa investor service take?
DLD publishes a service time of 7 to 10 business days on its Golden Visa investor page, as checked on 21 September 2026. A document clarification or an additional valuation step may sit outside that published service window.
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.