Non-resident mortgage costs beyond the deposit
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents+
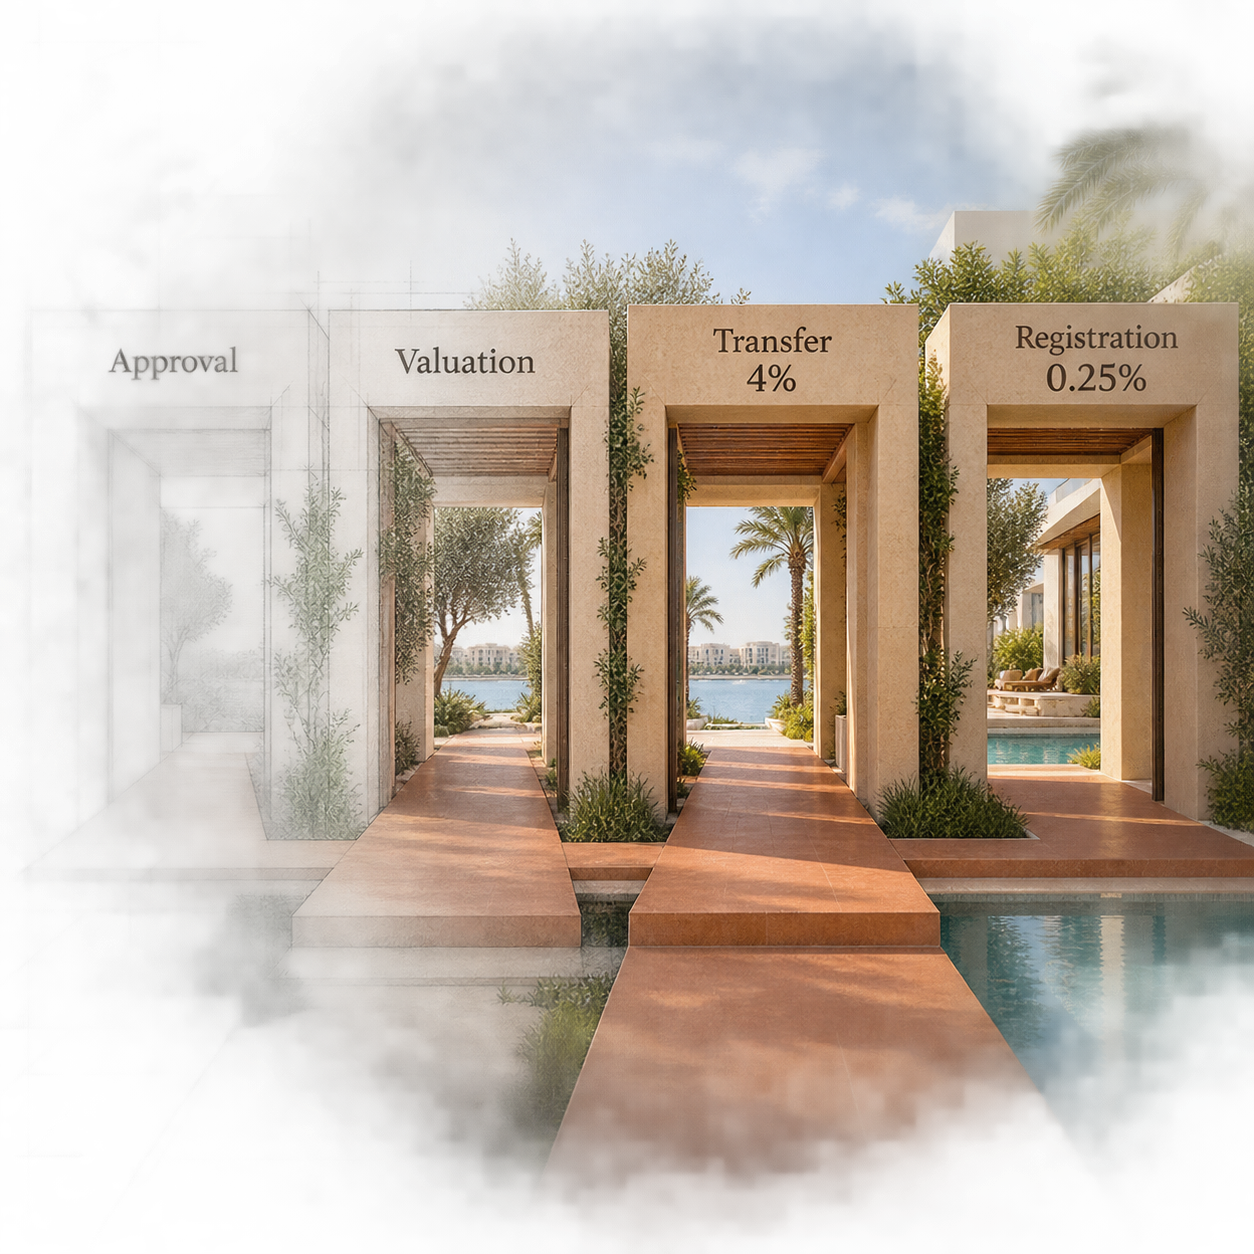
Dubai Land Department lists a 4% total sale-registration charge, split as 2% seller and 2% buyer on its ordinary completed-property service, plus a mortgage-registration charge of 0.25% of the mortgage value, as of 20 September 2026. For a non-resident buyer, the published buyer share sits outside the deposit, alongside the lender's own approval, valuation and insurance charges.
The cash ledger has four payment moments
The costs do not necessarily arrive together. Mashreq's cited KFS publishes the bank amounts but does not establish the collection point for each one, so pre-approval, valuation, processing and insurance timing must be confirmed in the final offer. DLD's cited pages separately identify the sale and mortgage-registration service charges.
The bank-variable rows are intentionally not turned into a Dubai-wide range. HSBC's customer tiers provide a second named example, not a blended market norm.
CBUAE ceilings do not set a non-resident offer
The official LTV limit is the outside boundary for regulated lenders. It does not require a bank to lend at that percentage. The CBUAE mortgage regulation states that lenders may adopt more conservative limits and defines LTV against the residential property's appraised value.
The CBUAE's accessible Financial Stability Report 2024 publishes the expatriate ratios below. They are dated to that report's 2024 period; a bank's current offer can use lower ratios.
For someone living in the UK, India or another GCC country, the written bank offer matters more than the regulatory maximum. A non-resident product can use a lower LTV, different eligibility filters or a smaller maximum loan. The accessible CBUAE mortgage-regulation PDF also requires an independent on-site valuation by a qualified third party before an irrevocable lending commitment.
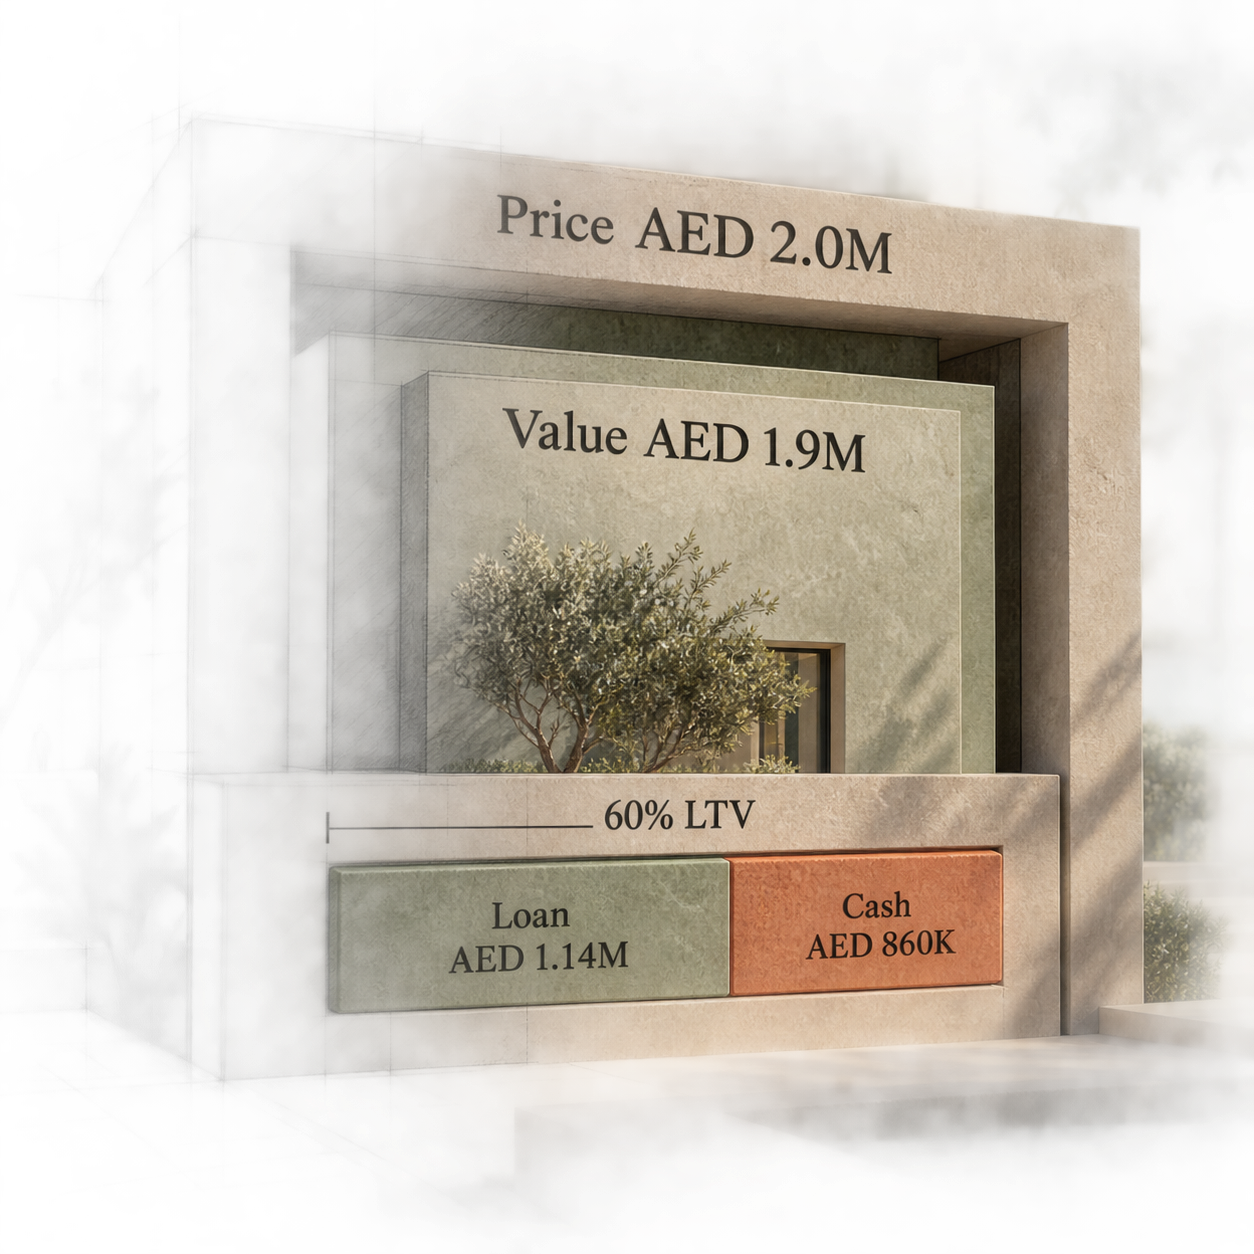
That creates two separate numbers. The purchase contract fixes what is owed to complete the sale. The bank's valuation helps fix how much the lender will advance. If those values differ, the buyer's cash fills the difference.
Approval and valuation charges stay in the bank ledger
The approval-stage ledger is bank-specific, so the bank's current Key Facts Statement and final offer letter are the controlling documents. A Key Facts Statement, or KFS, is the lender's standard disclosure of product terms, charges and examples.
Mashreq's KFS revised 19 June 2026 publishes an AED 1,050 pre-approval charge, a fresh-loan processing fee of 1.05% of the loan amount, an AED 2,625 property-evaluation fee and property insurance at 0.06% of property value. These figures are useful because they form one internally consistent lender example. They are not presented as the standard price across UAE banks.
The valuation fee pays for the lender's collateral assessment. It does not add to the property value and does not reserve the property. The accessible CBUAE mortgage-regulation PDF says the appraisal must be independent of the borrower, seller, developer or contractor and the loan decision process, as checked 20 September 2026.
Transfer and mortgage registration are separate DLD lines
The sale registration records the change of ownership. The mortgage registration records the financing entity's security over the property. They are related at completion, but DLD publishes different charges for each service.
For an ordinary completed-property sale, DLD's Property Sale Registration page lists seller 2% and buyer 2%, making 4% total, as of 20 September 2026. It also lists an AED 4,000 service-partner fee plus VAT where the price is at least AED 500,000, AED 250 for a villa or apartment map, AED 250 for title-deed issuance, AED 10 knowledge and AED 10 innovation.
For the mortgage-registration service, DLD lists 0.25% of the mortgage value, AED 250 for title-deed issuance, AED 10 knowledge and AED 10 innovation for each relevant drawing, and an AED 4,000 service-partner fee plus VAT, as of 20 September 2026. The UAE Federal Tax Authority's current VAT page shows 5%, making the AED 4,000 service fee AED 4,200 including VAT. This worked example uses that published ordinary mortgage-registration schedule and does not import an exemption from DLD's distinct mortgaged-property sale service.
DLD's pages expose different service routes and fee treatments. The booked trustee office and the lender can identify which route applies and whether registration occurs in one combined appointment. The current trustee-office transfer guide explains the transfer-day handoff, while the overseas buyer's title-check file covers the official records to reconcile before funds move.
Worked example: AED 2 million purchase, AED 1.9 million valuation
This example isolates cash mechanics. Its property price, valuation and approved LTV are hypothetical inputs. The bank fees come from Mashreq's June 2026 KFS, and the government charges come from the current DLD pages cited above.
Financing inputs
The AED 860,000 is the deposit or equity contribution in this example. It contains AED 760,000, which is 40% of the bank valuation, plus the AED 100,000 difference between the agreed price and the bank valuation.
Cash beyond that AED 860,000 equity
The AED 67,665 upfront subtotal follows the ordinary sale and mortgage-registration schedules cited beside the table. Adding Mashreq's AED 1,200 first annual insurance premium produces an illustrated first-year total of AED 68,865, but the cited KFS does not establish the insurance collection date. The example excludes DLD knowledge and innovation additions on the mortgage record because the mortgage page states AED 10 plus AED 10 for each relevant drawing without fixing the number of drawings for this hypothetical transaction. It also excludes contractual items not requested in this ledger, such as broker commission or a developer's own NOC charge.
A valuation shortfall is a cash-timing issue
The shortfall does not create a new DLD fee. It changes the split between lender money and buyer money. In the example, the lender advances AED 1.14 million because the assumed 60% LTV is applied to AED 1.9 million, not the AED 2 million contract price.
The buyer's equity therefore reaches AED 860,000 before AED 67,665 of worked upfront fees, plus the AED 1,200 first annual insurance premium under DLD's published split. If an approval was planned against the agreed price rather than the eventual appraisal, the extra AED 100,000 appears after valuation and before completion. That is why the valuation date belongs in the cash calendar, not only in the credit file.
The contract controls the buyer's obligations to the seller. The lender's final offer controls the approved loan. Any amendment, exit right or funding deadline depends on the actual contract and offer terms, so those documents need transaction-specific legal and banking review.
Build the ledger from documents, not remembered percentages
The shortest reliable file has one line for each payee and one source beside it. Use the lender's current KFS for bank charges, the final offer for the approved loan and collection dates, the valuation report for the appraised value, DLD's current service page for government charges, and the trustee's written appointment statement for the exact transfer-day amount.
Lock the bank charges
Record each pre-approval, processing, valuation and insurance amount from the current KFS and final offer. Keep lender examples separated by bank and customer tier.
Replace the expected value with the appraisal
Recalculate the loan from the value and LTV used in the written offer. Put any gap between that result and the contract price into the buyer-equity line.
Get the transfer statement
Ask the lender or booked trustee to itemise the DLD sale, mortgage-registration, service-partner and record charges for the selected service route.
Match payee and payment date
Keep approval cash, valuation cash and transfer-day instruments separate. Record the beneficiary and accepted payment channel exactly as issued for the transaction.
Sources used for the dated ledger
The regulatory ceilings come from the accessible CBUAE Financial Stability Report 2024 and are presented with that report period. The appraised-value definition, conservative-lending allowance and independent on-site valuation rule appear in the accessible CBUAE mortgage-regulation PDF. The government charges come from DLD's ordinary sale and mortgage-registration pages, both checked 20 September 2026. The named lender example comes from Mashreq's KFS revised 19 June 2026.
Can a non-resident get a mortgage in Dubai?
Is the DLD 4% charge included in the mortgage deposit?
No. The deposit is buyer equity against the purchase price. DLD's ordinary sale page lists the separate 4% government line as 2% seller and 2% buyer, as checked 20 September 2026.
What happens if the bank valuation is below the agreed price?
For a given approved LTV, the loan is calculated against the lender's appraised value. The purchase contract still uses its agreed price, so the difference increases buyer-funded equity unless the transaction documents provide another outcome.
Are mortgage processing and valuation fees the same at every bank?
No. Mashreq's KFS revised 19 June 2026 publishes a 1.05% processing fee and AED 2,625 valuation fee. HSBC's pages checked 20 September 2026 publish customer-tier arrangement fees and the same AED 2,625 valuation figure, illustrating why each lender must remain a named example.
When are mortgage-registration fees paid?
DLD's mortgage-registration page says the bank submits the electronic transaction and DLD fees are deducted from the bank account in that route. The lender and trustee can state how and when those amounts are collected from the borrower for the specific completion.
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.