Dubai First-Time Home Buyer Program (2026): eligibility, fees and QR code
Who qualifies for Dubai's first-home programme, what the QR code gives you, and which DLD, bank and developer fees still apply.
Published Updated
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents
Emirates NBD's First-Time Home Buyers campaign publishes AED 10,000 minimum salary and financing up to 85% for UAE nationals, versus AED 15,000 and up to 80% for expatriates (Emirates NBD, verified 18 October 2026). These campaign terms sit alongside Dubai Land Department (DLD) programme eligibility; meeting either set of criteria does not establish mortgage approval.
Source: withlida.com, 18 October 2026, from Emirates NBD's campaign benefits list. These are this bank's campaign terms by customer category, subject to its assessment, rather than programme-wide salary requirements or a loan offer. Loan-to-value (LTV) means the loan amount relative to the property's value.
Programme rules in this summary: DLD programme overview, verified 18 October 2026.
Last verified: 18 October 2026. Checked by the publication's independent check, 18 October 2026.
The short answer: what the programme gives a first buyer
The Dubai First-Time Home Buyer Program provides access to participating developer and bank offers while ordinary purchase costs remain. DLD describes it as an initiative for people buying their first home in Dubai, with benefits delivered through participating developers and banks (DLD, as of 18 October 2026).
The headline benefits sit in five buckets:
Source: withlida.com, 18 October 2026, from the DLD programme overview. The benefits described do not establish that every eligible applicant receives a particular offer.
The programme can change access to inventory, price offers, fee-payment timing and bank products. The ordinary purchase process remains, as explained in the full Dubai buying guide.
Who qualifies with DLD?
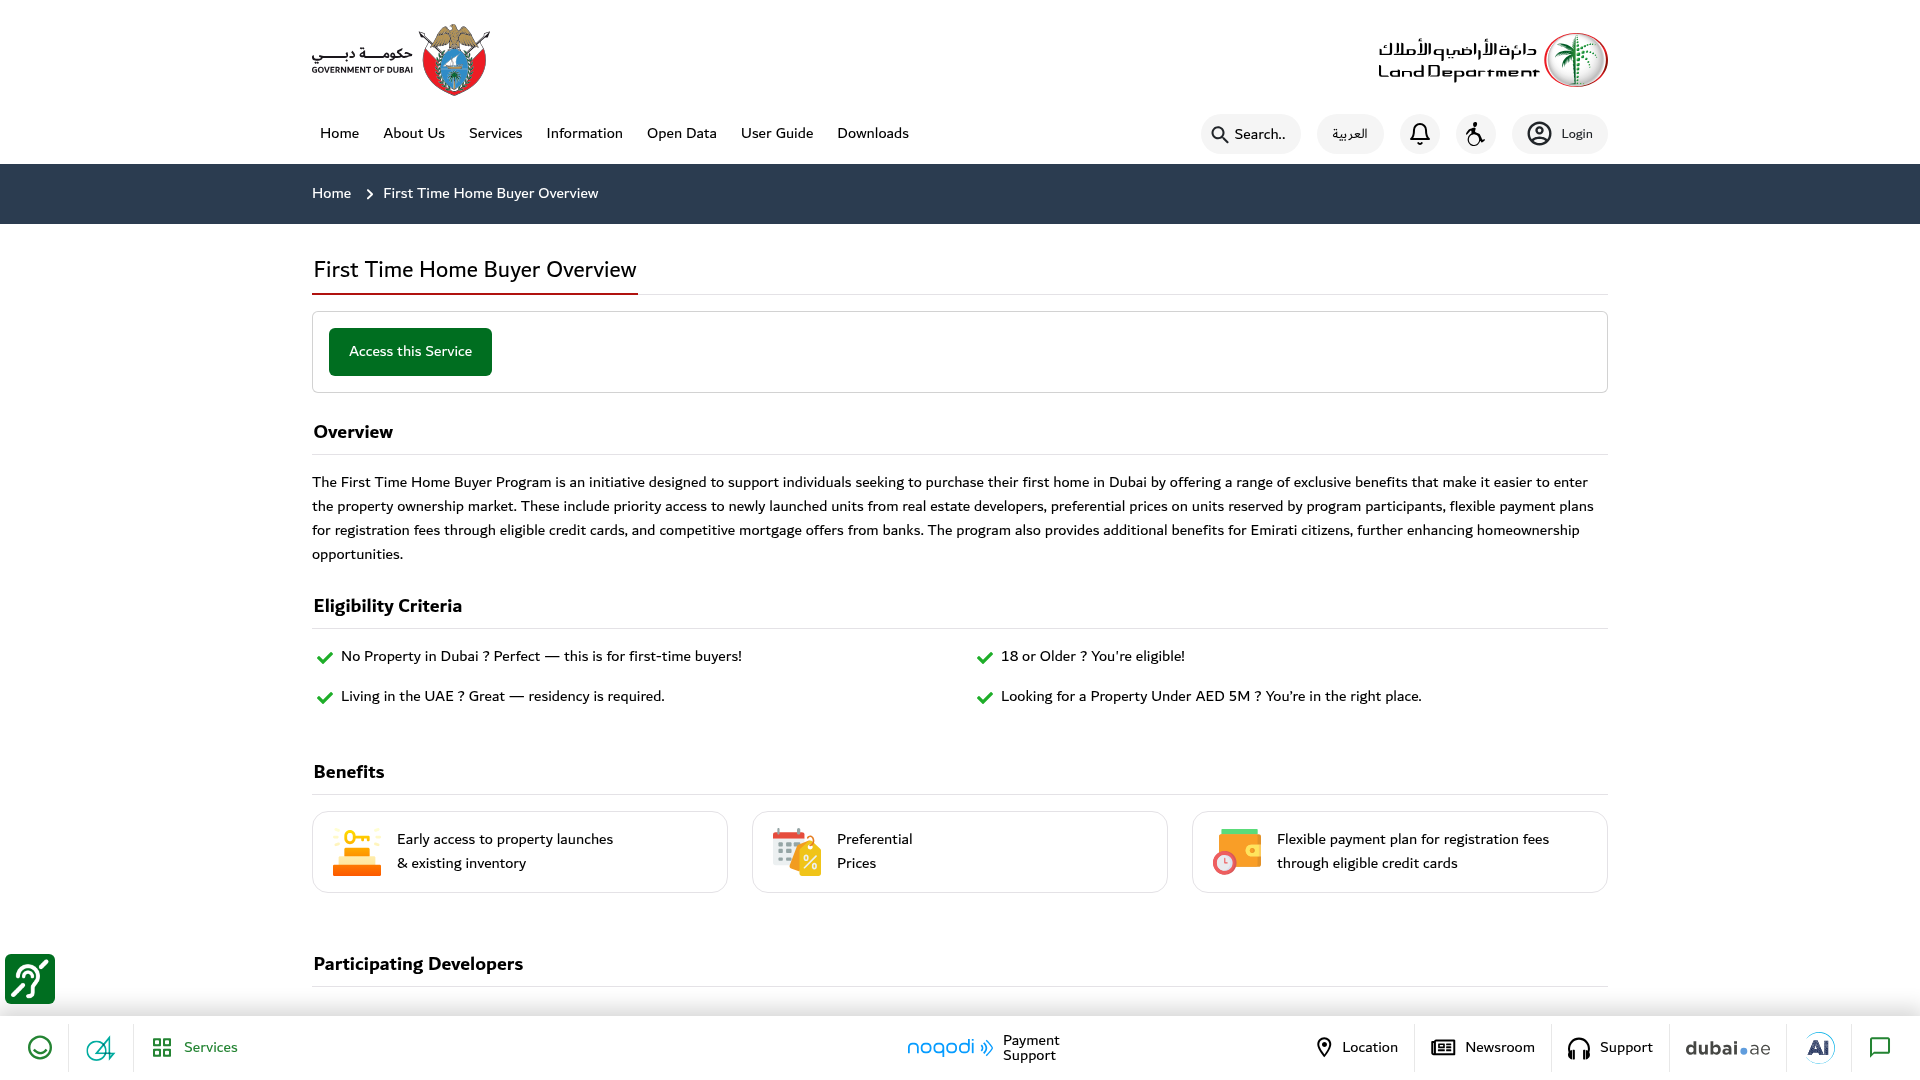
DLD requires UAE residency, adult age, no current Dubai freehold residential ownership and a sought property below its programme value limit. As of 18 October 2026, its overview lists these core conditions:
Source: withlida.com, 18 October 2026, from DLD's eligibility criteria and FAQs.
DLD also answers two edge cases directly. Owning property in another emirate does not disqualify the applicant, as long as they do not currently own freehold property in Dubai. Owning property in a non-freehold location also does not disqualify the applicant on its own, under that same condition. These are DLD's stated edge-case answers, verified 18 October 2026.
The DLD overview does not publish a programme-wide minimum salary. Mortgage income requirements belong to the participating bank's assessment. DLD also says a mortgage is not required to participate (DLD, as of 18 October 2026).
What does the QR code establish?
The QR code establishes that DLD has confirmed programme eligibility; it does not establish mortgage approval, a property purchase, a discount or a developer allocation. DLD says applicants register through its website or Dubai REST, DLD's property-services app, submit the required information and, if eligible, receive a confirmation email containing their First-Time Home Buyer QR code (DLD, as of 18 October 2026).
The QR code supports three separate stages:
DLD eligibility confirmation
The confirmation is the programme credential. A partner's offer and any purchase or financing agreement require their own terms and assessment.
Participating developer contact
DLD says selected developers contact eligible registered buyers ahead of project launches. Notifications and access do not establish an allocation or require the applicant to buy.
Partner-bank discussions
DLD says registered and confirmed buyers may approach participating banks about programme mortgage offerings. Emirates NBD separately evaluates applications under its credit policies, including the customer's eligibility and borrowing capacity.
Stage sources: DLD programme overview and Emirates NBD campaign, verified 18 October 2026.
DLD says the QR code remains valid until the buyer has purchased a property and registered it with DLD. If the applicant registers without finding a suitable property, registration remains valid, with priority launch notifications during the programme period. Once a property is bought under the programme, the buyer loses First-Time Home Buyer status and cannot participate again, even after selling it (DLD, as of 18 October 2026).
A registered eligible buyer may approach participating banks and developers, but DLD limits benefit use to one partner real estate developer and one participating bank. The ability to approach several partners does not establish an entitlement to combine their benefits (DLD, as of 18 October 2026).
Which fees remain?
DLD says there is no additional fee to apply or participate, while standard DLD registration fees and any developer or bank charges still apply unless a special programme offer specifies otherwise (DLD programme overview, as of 18 October 2026). No participation fee therefore does not mean a purchase has no transaction costs.
The official DLD sale-registration schedule, reopened on 18 October 2026, retains the following percentage and document lines. A title deed is the ownership record issued through registration.
Source: withlida.com, 18 October 2026, from DLD Property Sale Registration.
The property/map entries and service-partner tiers are shown separately because their applicability depends on the file and registration channel. A Real Estate Registration Trustee is a DLD service partner that processes registrations through its service centre.
Source: withlida.com, 18 October 2026, from DLD Property Sale Registration. Map categories and partner tiers are alternatives according to applicability; these rows are not a universal package to add together.
The schedule's party labels also need to be distinguished from the agreed allocation. Contract F, DLD's property sale agreement, records the seller's and buyer's transfer-fee allocation in clause 11 (DLD Contract F, verified 18 October 2026). This guide does not assume that the buyer funds every scheduled charge.
Fee-payment timing is a separate issue. DLD's programme overview describes interest-free instalment plans for registration fees through eligible credit cards. The applicable card and provider terms need confirmation; the description does not establish a universal reduction in the registration fee (DLD, as of 18 October 2026).
The Dubai property registration fees guide, refreshed on 16 October 2026, sets out detailed arithmetic with explicit transaction, channel and payer assumptions. A programme applicant's wider cost record also includes applicable developer, bank and separately agreed professional charges. No universal transaction total is stated here.
Which programme channels cover ready and off-plan property?
DLD describes developer channels for off-plan benefits and participating-bank channels for ready-property benefits. These channels involve separate eligibility and offer checks, as of 18 October 2026.
Source: withlida.com, 18 October 2026, from the DLD programme overview and Emirates NBD's separate campaign assessment terms.
Programme confirmation does not itself establish a purchase, discount, unit allocation or particular financing outcome. DLD says a mortgage is not required for participation. For a ready-property sale, the ordinary registration process remains, including the developer's e-NOC, an electronic no-objection certificate, in freehold areas as listed on the DLD sale-registration service, verified 18 October 2026.
What salary and LTV does this bank publish by applicant group?
Emirates NBD publishes different campaign salary and financing limits for UAE nationals and expatriates, as set out in the attributed table at the top of this page. Those categories must remain attached to their figures. They are not a DLD programme-wide income test, an approval decision or a statement of lending terms at every participating bank (Emirates NBD campaign, as of 18 October 2026).
The bank lists availability for salaried and self-employed applicants, no application fee and the opportunity to apply with a co-borrower, all subject to terms. The salary rows do not establish a self-employed income test or a rule for combining applicants' salaries. Emirates NBD reserves the right to assess applications under its credit policies; rates and benefits depend on customer segment, eligibility, borrowing capacity, credit policy and central bank regulation (same campaign, verified 18 October 2026).
Is the displayed starting rate a current personal offer?
The displayed rate starting from 3.99% is a conditional campaign headline, rather than a personalised mortgage quote. Emirates NBD's embedded calculator separately states that its EIBOR reference was calculated using 4 November 2024. EIBOR is the Emirates Interbank Offered Rate, the benchmark referenced by the calculator. The page says the applicable rate is calculated using current EIBOR at loan disbursal (Emirates NBD, verified 18 October 2026).
The calculator's historical sample does not establish a rate available today. Its tentative rate, sample borrowing amount and monthly repayment are not reproduced here as current terms. A bank's dated written offer establishes the terms offered to an assessed applicant.
Can joint buyers participate?
Yes, when both individuals are eligible: DLD says a joint purchase under the programme is permitted only between people who both qualify. A qualifying applicant cannot use the programme jointly with someone who is ineligible (DLD, as of 18 October 2026).
Emirates NBD's campaign separately mentions the opportunity to apply with a co-borrower, subject to its terms. That bank feature does not change DLD's requirement for both joint purchasers to qualify or establish a joint loan approval (Emirates NBD campaign, verified 18 October 2026).
How to register and use the programme
Registration begins with DLD, followed by separate partner discussions and any subsequent transaction. DLD says applicants register via its website or Dubai REST and submit the required information (DLD, as of 18 October 2026).
Register with DLD
Use the DLD First Time Home Buyer service page or Dubai REST. DLD checks the application against the programme criteria. If ineligible, the applicant receives the reason and may reapply if circumstances change and all criteria are subsequently met.
Receive the QR code
If eligible, the applicant receives DLD's confirmation email with the programme QR code. This confirms programme eligibility and provides the credential for partner discussions.
Check the applicable channel
Participating developers provide the relevant project offer terms; participating banks assess mortgage applications separately. Eligible credit-card fee-payment arrangements have their own provider terms.
Verify the transaction costs
Any proposed purchase needs its applicable reservation or sale terms, bank offer if financed, and itemised registration charges. Map and service-partner entries depend on the transaction, with agreed payers identified separately.
Register any purchase
DLD says the QR code remains valid until purchase and registration. A purchase under the programme ends first-time status; a subsequent sale does not restore it.
Process sources: DLD programme overview, DLD sale-registration service and Emirates NBD campaign, verified 18 October 2026.
The five participating banks listed by DLD are Commercial Bank of Dubai, Dubai Islamic Bank, Emirates NBD, Emirates Islamic and Mashreq Bank. DLD's live partner-developer list is the place to verify current participation. For historical context, DET reported over AED 5 billion in programme sales and 22 participating developers on 8 June 2026; that count describes its release date (DLD overview, verified 18 October 2026; Dubai DET, 8 June 2026).
This specific programme starts with UAE residency. The country-origin context in the UK buyer guide does not replace DLD's programme eligibility screen.
FAQ, verified 18 October 2026
What is the first-time buyer scheme in Dubai?
It is a DLD and Dubai DET programme for eligible UAE residents, with participating-developer offers, eligible credit-card registration-fee payment plans and partner-bank mortgage offers. Programme eligibility does not establish a discount, allocation or mortgage approval (DLD, as of 18 October 2026).
Who is eligible for Dubai's First-Time Home Buyer Program?
DLD requires UAE residency of any nationality, age 18 or older, no current freehold residential property in Dubai and a sought property below AED 5 million. DLD's overview does not publish a programme-wide minimum salary, and a mortgage is not required to participate (DLD, as of 18 October 2026).
Does the programme remove the DLD registration fee?
There is no additional application or participation fee, but standard DLD registration and developer or bank charges remain unless a special programme offer specifies otherwise. DLD also describes interest-free registration-fee instalments through eligible credit cards, which concern payment arrangements rather than a universal fee reduction (DLD, as of 18 October 2026).
What is the minimum salary for a first-time home buyer mortgage in Dubai?
DLD does not publish a programme-wide salary threshold. Emirates NBD's specific First-Time Home Buyers campaign lists AED 10,000 for UAE nationals and AED 15,000 for expatriates, with financing up to 85% and 80% of property value respectively. These campaign criteria remain subject to the bank's separate assessment and do not establish loan approval (DLD overview and Emirates NBD campaign, verified 18 October 2026).
Can two people buy together under the programme?
Yes, only when both individuals are eligible under DLD's programme. A bank's separate co-borrower option does not change that programme requirement or establish joint mortgage approval (DLD overview and Emirates NBD campaign, verified 18 October 2026).
How long is the First-Time Home Buyer QR code valid, and can it be used again?
DLD says the code remains valid until the buyer purchases and registers a property with DLD. A purchase under the programme ends first-time status, and selling that property later does not restore programme eligibility (DLD, as of 18 October 2026).
Can I approach more than one participating bank or developer?
Yes. Eligible registered applicants may approach participating partners, whose offers can differ, but DLD limits benefit use to one partner developer and one participating bank (DLD, as of 18 October 2026).
Does Emirates NBD's calculator show today's available mortgage rate?
The campaign's displayed starting rate is conditional, and its calculator identifies a historical EIBOR reference date of 4 November 2024. Emirates NBD says the applicable rate uses current EIBOR at disbursal; the sample does not establish a current personal offer (Emirates NBD, verified 18 October 2026).
Change log: 2026-10-18 · refreshed · Corrected Emirates NBD's previously combined campaign criteria: UAE nationals, AED 10,000 minimum salary and financing up to 85%; expatriates, AED 15,000 and up to 80%. Clarified the conditional starting rate and the calculator's historical EIBOR reference. Reverified DLD eligibility, joint purchasers, QR validity, repeat use, fee-payment flexibility and sale fees; separated conditional charges and replaced buyer-profile recommendations with programme-channel checks. Sources: Emirates NBD campaign, DLD programme overview, DLD Property Sale Registration and DLD Contract F, verified 18 October 2026.
- Last updated
- Published Jul 8, 2026
- Category
- Buy
 Lida Moghaddam
Architect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.