Non-resident mortgage approval file: LTV, income and valuation evidence
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents+
The CBUAE ceiling for an expatriate first owner-occupied home of AED 5 million or less is 80%, but current non-resident product pages publish lower lender limits: HSBC says up to 60%, while Mashreq's detailed FAQ says up to 50% of fair market value. Those figures, checked 25 September 2026, belong in separate columns because regulation, applicant pre-approval, property valuation and the final offer answer different questions.
The approval file has three gates, not one
Pre-approval, valuation and the final offer are separate because the lender is answering a different question at each stage. FAB's current non-resident process puts an approval in principle before property valuation, then asks for final documents before the offer letter and mortgage approval (FAB, checked 25 September 2026).
An approval in principle, or AIP, is the lender's preliminary estimate of how much an applicant may be eligible to borrow. It is about the person and the stated finances. Valuation comes after a property is selected and tests the collateral. The final offer brings the accepted applicant, appraised property and approved terms into one document.
The table is a workflow, not a universal checklist. FAB names its mortgage application form, income proof and sale and purchase agreement at the final-document stage. Its page also says other items may be requested by the mortgage specialist. The issued lender checklist therefore controls the live file.
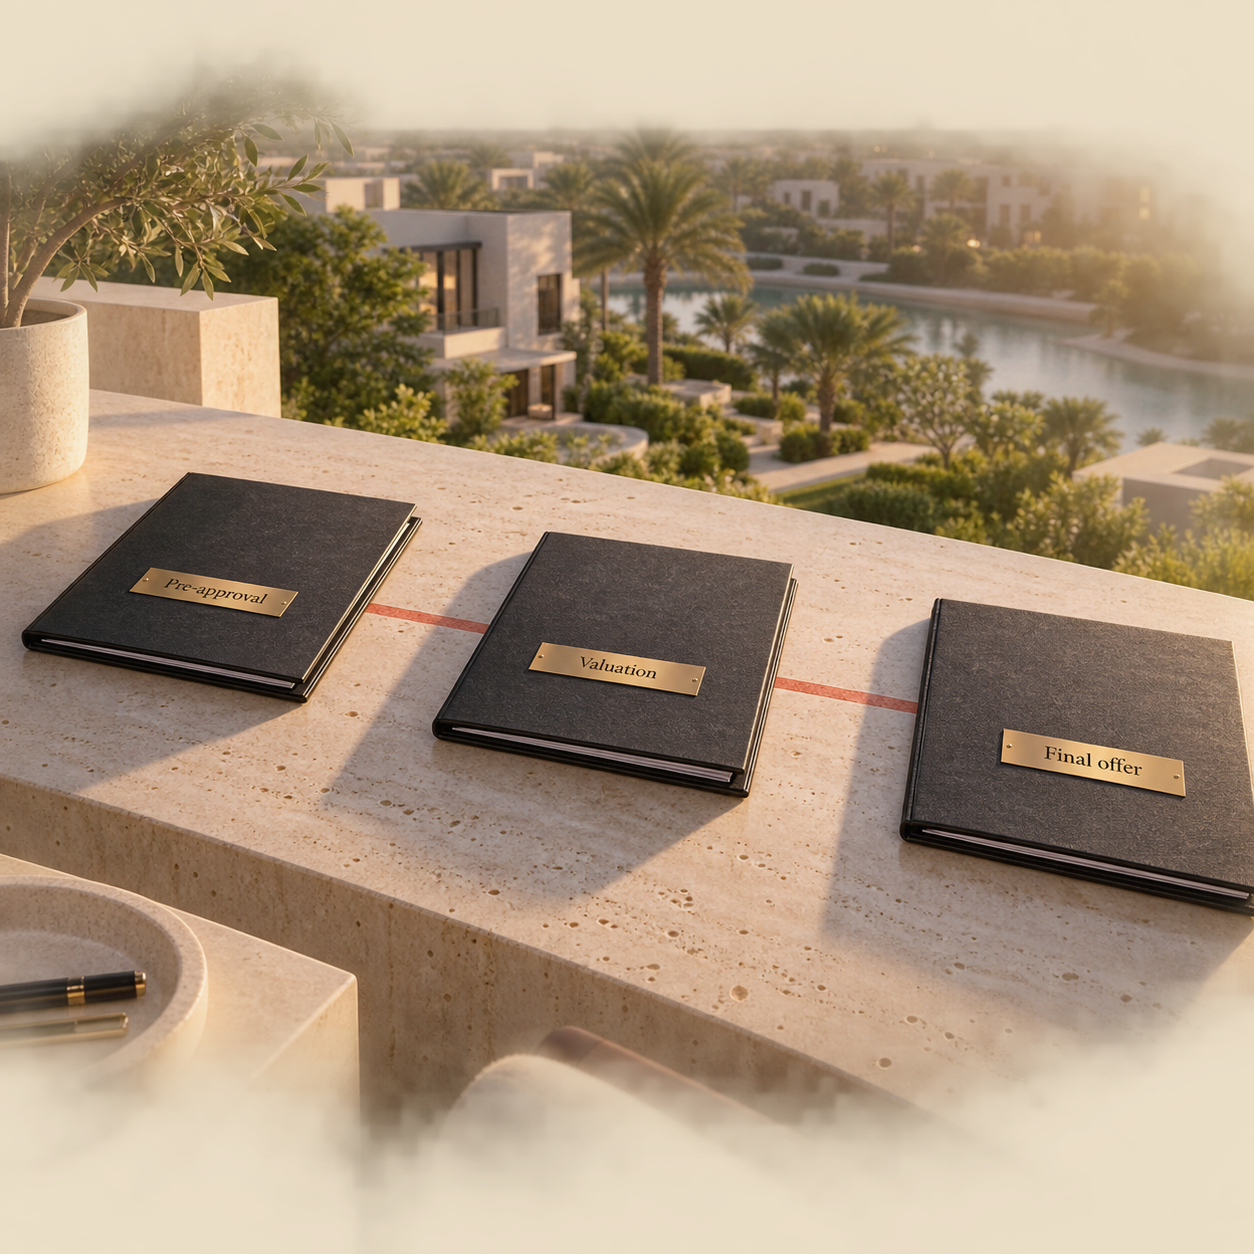
For the wider purchase route around these stages, start with the current non-resident mortgage pillar. This companion stays with the evidence file.
Start with the regulatory ceiling, then record the lender limit
The CBUAE schedule sets the outside boundary. It does not set the percentage a named bank must offer to a non-resident. The official mortgage regulation permits lenders to use more conservative limits, while the live Rulebook publishes the current expatriate caps (CBUAE Rulebook, checked 25 September 2026; CBUAE Circular 31/2013, fetched 25 September 2026).
Loan-to-value, or LTV, is the loan outstanding divided by the appraised value of the residential property. That definition matters: the percentage applies to the lender's accepted value, not automatically to the agreed purchase price (CBUAE Circular 31/2013, fetched 25 September 2026).
Other CBUAE ceilings also sit above the lender's assessment. The live Rulebook sets a 50% debt-burden ratio, or DBR, for gross salary and regular income from a defined source, a maximum mortgage tenor of 25 years, and an expatriate financing cap of up to seven years of annual income, all checked 25 September 2026. The same page says providers must assess the borrower's circumstances rather than automatically apply the maximum DBR.
The clean file therefore keeps four fields distinct: CBUAE category cap, lender's published product maximum, AIP estimate, and final approved LTV. Combining them into one percentage creates a number that no source actually issued.
What three current bank pages actually prove
The three lender pages overlap on the existence of a non-resident route, but they publish different boundaries and different parts of the evidence list. None proves what another bank will accept.
Sources: HSBC UAE, FAB and Mashreq NEO, all fetched 25 September 2026.
The Mashreq page's two LTV statements are kept separate because the page itself uses both. The detailed FAQ attaches 50% to fair market value, while the hero states 60% of property value. The current written terms must resolve which limit and value basis apply to an actual file.
HSBC also publishes timing and cost details that belong only to its route. Its page says arranging a home loan may take up to 14 working days in most cases, depending on circumstances, and lists a standard valuation fee of AED 2,625 including VAT, as checked 25 September 2026. FAB publishes no AIP fee and a maximum loan amount of AED 10 million on its named non-resident page. Mashreq publishes a maximum loan of AED 10 million and tenor of 25 years. These are named product facts, not UAE-wide norms.
Build the income evidence index without filling gaps from memory
The regulator requires effective verification, but the lender decides which current documents satisfy it. CBUAE Circular 31/2013 says the lender must verify income and other financial information and retain the documentary evidence supporting its decision (fetched 25 September 2026). It does not create one public checklist for every applicant country, employment type or bank.
A source-clean index has three sections:
- Published lender requirements. Copy only what the selected lender currently names. Mashreq's fetched page names the application form, passport and three months of bank statements. FAB names income proof but does not define the form of that proof on the fetched page. HSBC's non-resident page states its account relationship requirement but does not publish an itemised income pack there.
- Issued additions. Record each extra item from the bank's live checklist exactly as issued, with the request date and applicant name. This prevents a document used by one bank or applicant type from becoming an unsupported market-wide rule.
- Reconciliation status. Mark submitted, accepted, replacement requested or pending. Keep the evidence name separate from the conclusion the lender draws from it.
This structure also works for a self-employed applicant without inventing a standard pack. Mashreq's current page says salaried and self-employed people may apply, subject to the bank's discretion, but its fetched page does not publish a separate self-employed document schedule. That missing detail belongs in the issued-additions section after the lender supplies it.
Valuation changes the loan amount, not the contract price
A valuation shortfall changes the financing split because CBUAE defines LTV against appraised value. The purchase price remains the contract input; the bank's accepted appraisal becomes the loan input. FAB's page separately says an applicant may need to evidence the difference between the loan amount and property purchase amount, while Mashreq says fair market value is set by its approved independent valuation agency, both checked 25 September 2026.
This illustration uses hypothetical inputs, not a product quote. Every amount was independently recomputed in calculations.py.
The AED 150,000 appraisal gap does not become AED 150,000 of extra cash relative to a plan built at the same 55% LTV. The loan falls by 55% of that gap, AED 82,500. The remaining AED 67,500 is the buyer-funded 45% share that was already present in the price-based equity plan. The recomputed identity is AED 1,080,000 plus AED 82,500 equals AED 1,162,500.
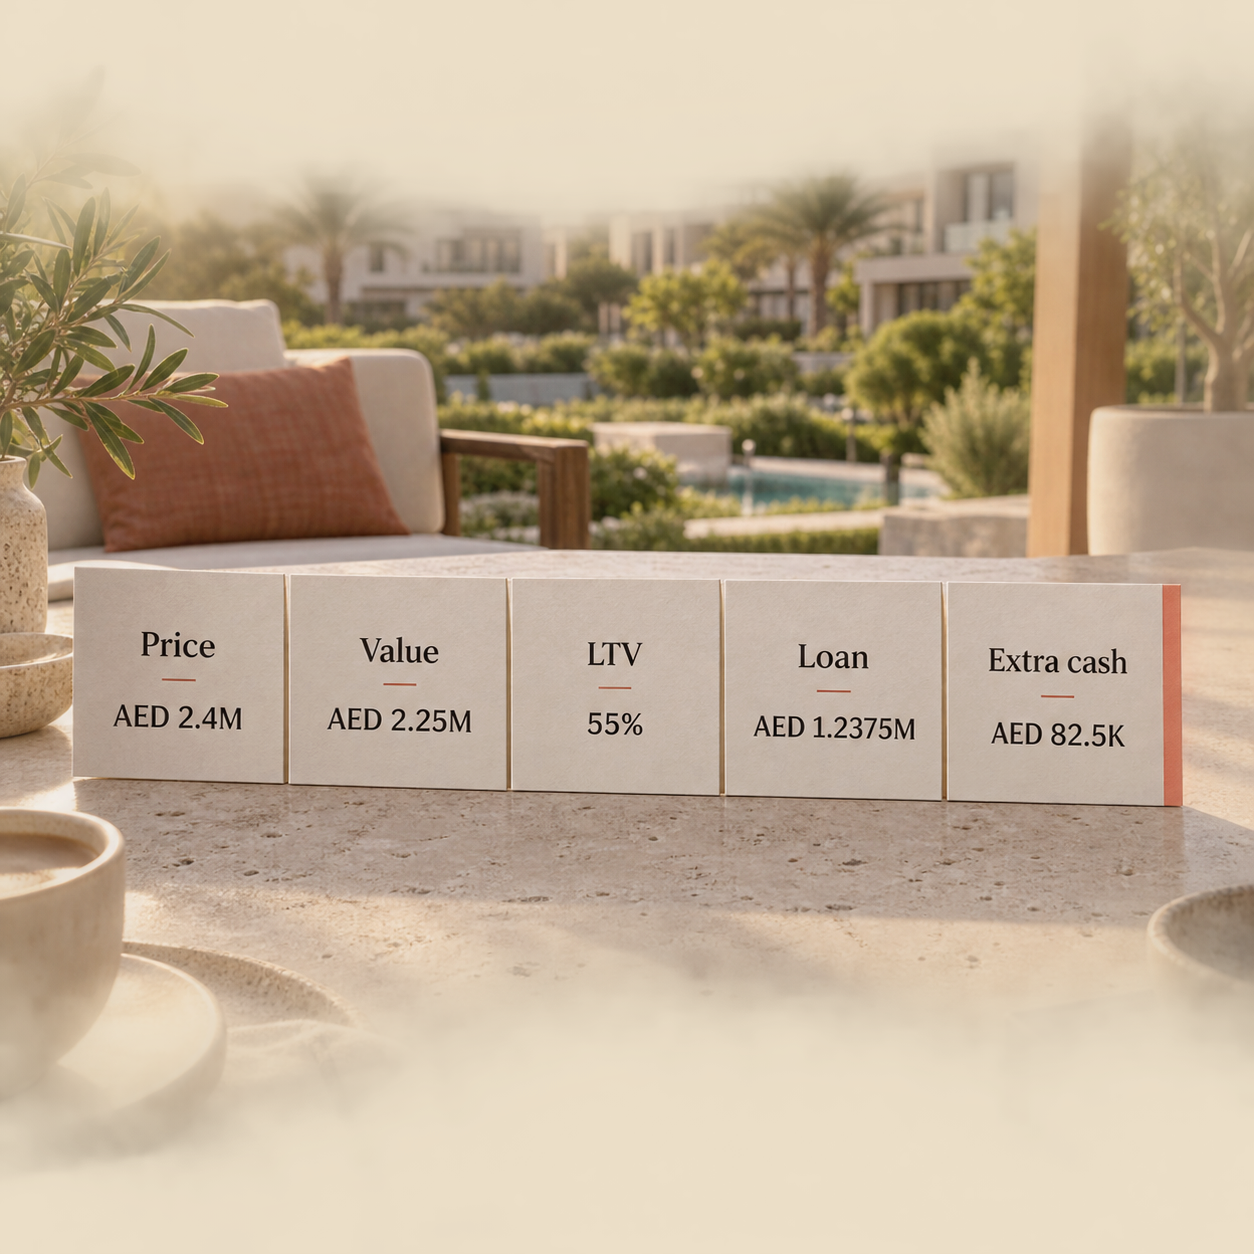
This example excludes fees so the valuation effect remains visible. The current sibling guide holds the separate non-resident mortgage cash ledger.
Reconcile the final offer before the purchase handoff
The final offer is the first stage where the approved applicant, accepted property value and loan terms can be checked in one place. CBUAE's mortgage regulation says loan documentation should include the property, borrower contribution, loan amount, repayment period, periodic instalment, interest or profit rate, insurance requirement and disbursement method (Circular 31/2013, fetched 25 September 2026).
Freeze the applicant evidence index
Record the exact version and date of each item the lender accepted. Keep unresolved requests visible rather than treating submission as acceptance.
Attach the valuation outcome
Record the appraised value used by the lender, the valuation date and the property identifier. Recompute the loan from the approved LTV and that accepted value.
Reconcile pre-approval with the offer
Compare the AIP estimate with the final loan amount, borrower contribution, tenor, instalment, rate or profit basis, insurance requirement and conditions. A change is recorded as a change, not blended into the earlier estimate.
Separate the next cash ledger
Move valuation charges, bank charges and completion funds into the dated cash file. Do not let a correct loan amount conceal a missing payment line.
The result is a traceable file: the regulator supplies the ceilings, each lender supplies its own eligibility and evidence requirements, the valuer supplies the accepted property value, and the final offer supplies the approved terms. No one document does all four jobs.
Dated FAQ, 25 September 2026
Can a non-resident get a mortgage in Dubai?
Yes. HSBC, FAB and Mashreq each had a live non-resident UAE mortgage page when checked 25 September 2026. Eligibility, property acceptance, loan amount and final approval remain specific to the lender and file.
What documents does a non-resident need for a Dubai mortgage?
There is no single list proved by the three current pages. Mashreq names an application form, passport and three months of bank statements; FAB names an application, income proof and sale and purchase agreement at final review; HSBC publishes an account-eligibility requirement. The bank's issued checklist controls the application.
Can a self-employed non-resident apply for a Dubai mortgage?
Mashreq's current non-resident page says its product is available to salaried and self-employed applicants, checked 25 September 2026. That page does not publish a separate self-employed evidence schedule, so the bank's issued list supplies the missing detail.
What happens if the bank valuation is below the purchase price?
At an unchanged approved LTV, the loan falls because CBUAE defines LTV against appraised value. In the illustrative calculation, a valuation of AED 2,250,000 rather than the AED 2,400,000 price reduces a 55% loan by AED 82,500.
Is pre-approval the same as a final mortgage offer?
No. FAB's current process places approval in principle before property valuation and final documentation, then issues the offer letter after approval. The AIP is an estimate of borrowing eligibility; the final offer records the approved terms for the accepted property and applicant.
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.