Dubai mortgage pre-approval expiry: a non-resident refresh calendar (2026)
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents+
HSBC UAE says its Approval in Principle is valid for 60 calendar days, but it also says the document is only an indication of possible lending, not a home-loan guarantee, accessed 28 September 2026. For a non-resident buyer, the issued letter and named lender set the validity window; property valuation, the final mortgage offer and Dubai transfer evidence remain separate records.
The lender and letter control the validity window
Validity belongs to the issuer because an Approval in Principle is a lender's early assessment, not a rule made for every Dubai mortgage. HSBC describes it as an indication of how much the institution may be willing to lend after an initial assessment. The same HSBC page says its pre-approval is not a home-loan guarantee and publishes a 60-calendar-day validity period, accessed 28 September 2026.
That is one named issuer's statement. It does not establish the period used by another bank, and it does not replace the date or conditions printed on an issued letter. HSBC's separate non-resident mortgage page confirms a service route for buyers living outside the UAE, accessed 28 September 2026, but it does not publish a different non-resident validity period there.
The best-fit reading is narrow: use the pre-approval as search-stage evidence of the lender's preliminary view, then use the letter itself for the live date window. The broader applicant, LTV and valuation file sits in the non-resident mortgage approval guide.
Each evidence stage answers a different question
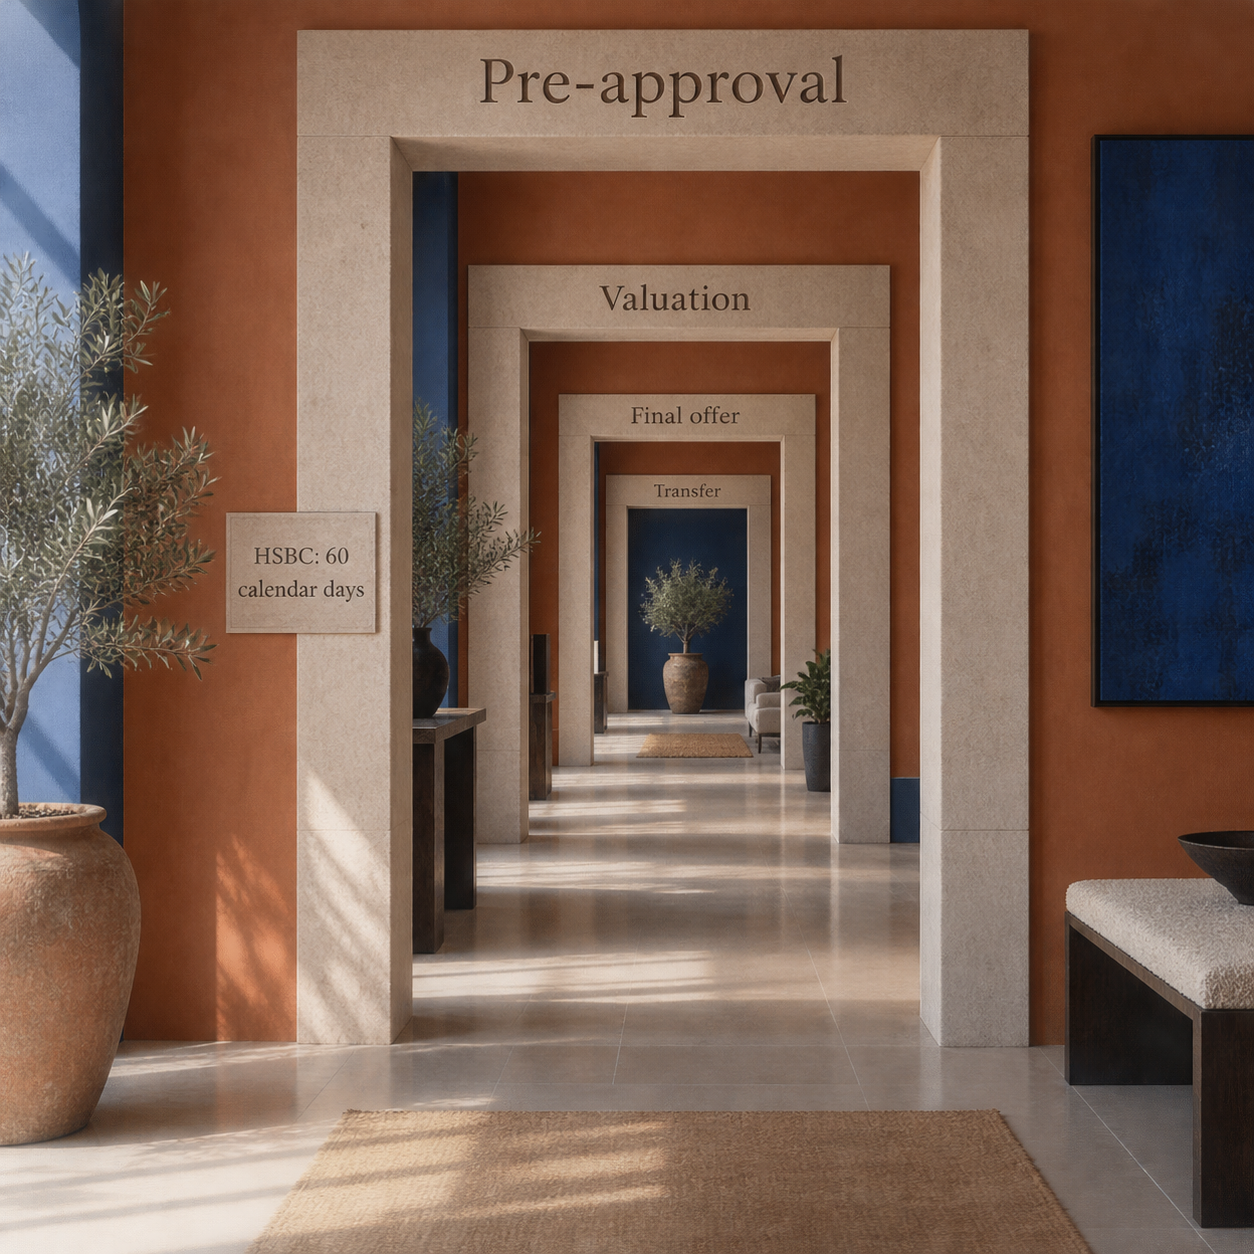
The stages stay separate because each record tests a different part of the purchase. HSBC's current application guide moves from Approval in Principle to a full mortgage application. Its buying guide says the lender conducts a valuation after a property is found. FAB's current non-resident process then distinguishes valuation, final decision, offer-letter acceptance, registration and disbursal. All three lender pages were accessed 28 September 2026.
This is also why a valuation gap belongs to a different calculation. The worked cash effect is covered in the mortgage valuation shortfall ledger, not in the pre-approval expiry clock.
A 60-day worked calendar from 28 September 2026
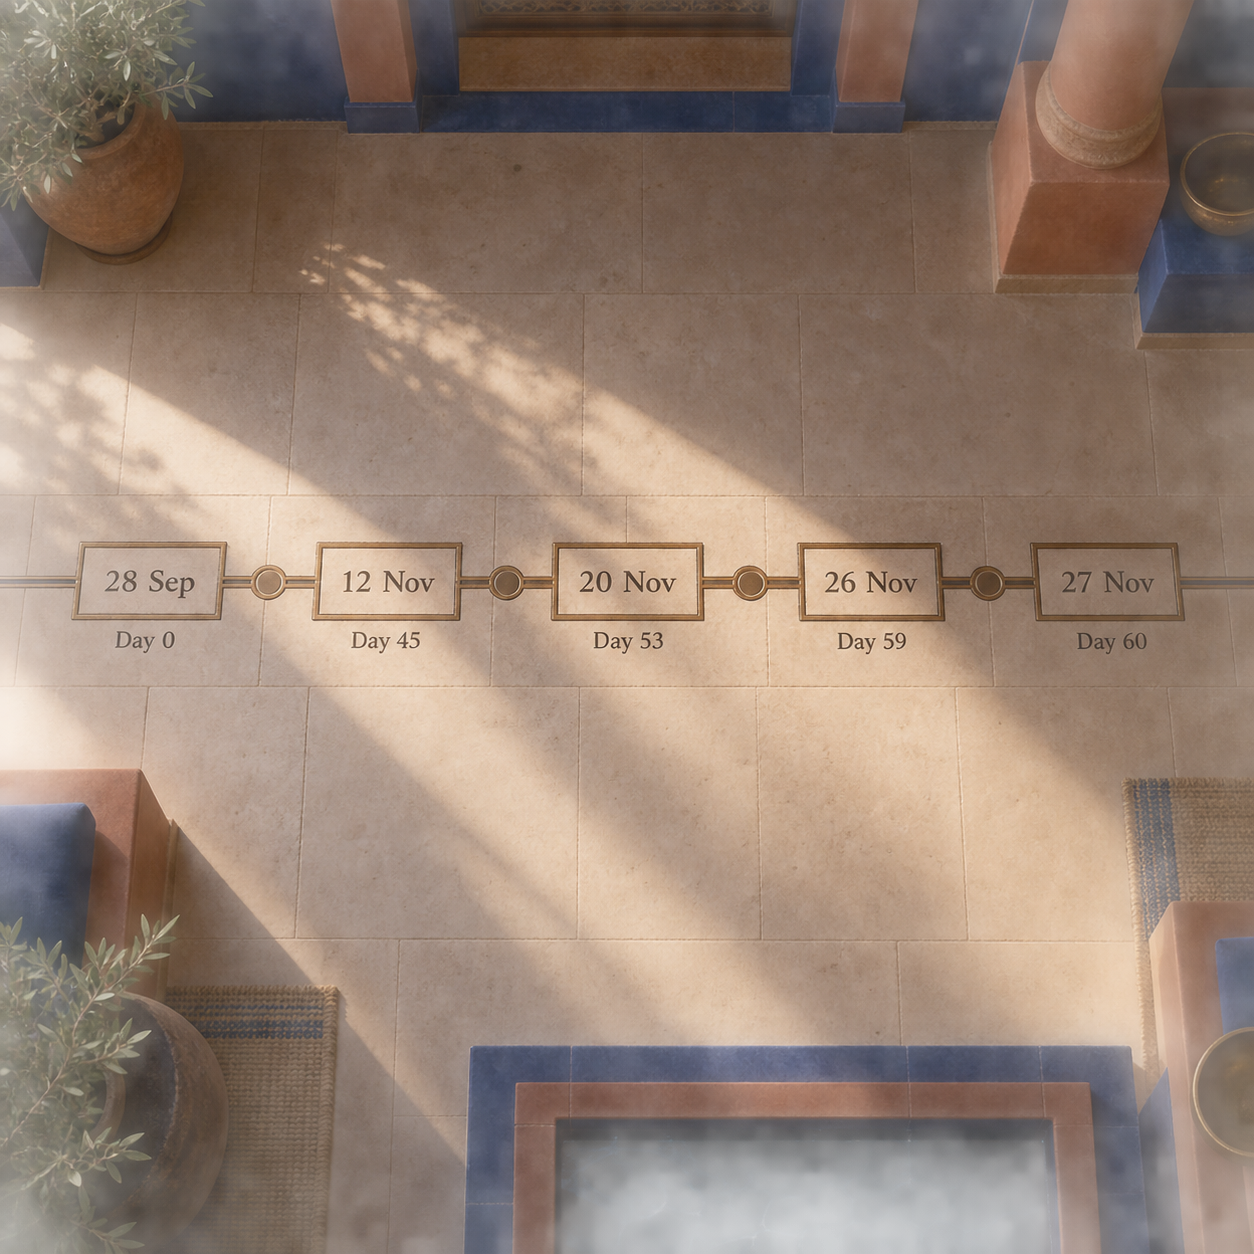
The worked calendar declares 28 September 2026 as an illustrative issue date and adds 60 elapsed calendar days. With the issue date labelled Day 0, the arithmetic endpoint is 27 November 2026. HSBC's published 60-calendar-day AIP period, accessed 28 September 2026, supplies the only lender-returned duration; every date below is calculated locally.
The two checkpoints are planning markers created for this example. They are not HSBC deadlines and they do not extend or shorten the issued letter. The lender document decides whether its end date is inclusive, what time cut-off applies and what process is available if the search continues.
Refresh the changed inputs, not the stage labels
The full application can reopen applicant and property evidence because it is a later decision. HSBC's application page, accessed 28 September 2026, says applicants may need identity documents, a personal bank statement dated within the past 6 months, a salary certificate, property ownership documents and proof of down-payment funds. It also says the full application involves a credit-bureau check.
Those are HSBC's published fields, not a universal renewal checklist. For an overseas buyer whose search is still running, the useful comparison is between the data behind the issued AIP and the data available now:
The lender decides which fields need to be resubmitted and whether a changed field affects the file. A fresh document does not turn pre-approval into valuation or a final offer; it updates evidence within the lender's process.
Read the later records on their own terms
The final mortgage offer becomes the loan-stage record because it follows the lender's property and applicant review. FAB's non-resident mortgage process, accessed 28 September 2026, separates the signed offer letter and mortgage terms from later registration and disbursal.
DLD's transfer service answers another question again. Its Property Sale Registration page, accessed 28 September 2026, names a valid passport as identity evidence for a non-resident foreign buyer and a developer e-NOC in freehold areas, then lists the electronic title deed and map as service outputs. The page carries no page-specific revision date, so the access date is used here; its site-wide footer timestamp is not treated as a revision date.
The practical conclusion is a record hierarchy, not one all-purpose approval: the AIP frames the early search, the valuation tests the selected property, the final offer records the lender's terms, and the DLD output records the completed registration stage.
FAQ, checked 28 September 2026
How long does a Dubai mortgage pre-approval last for a non-resident?
There is no single Dubai-wide period in the evidence used here. HSBC UAE publishes 60 calendar days for its Approval in Principle, accessed 28 September 2026; another lender's document may state a different period, and the issued letter controls its own cut-off.
Does mortgage pre-approval mean the property has been valued?
What can change after pre-approval?
HSBC's full-application page, accessed 28 September 2026, names current personal, income, liability, bank, property and down-payment evidence, plus a full credit-bureau check. The lender decides which changed inputs affect the application.
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.