Mortgage liability letter: request, validity and transfer sequence
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents+
As of 19 September 2026, DLD's mortgaged-sale service requires the seller's bank liability letter at registration and completes the sale only after the bank's mortgage-release letter is submitted. The practical consequence is simple: the request needs to be timed so the buyer's funding, developer e-NOC and trustee file can move within the validity dates printed by the seller's own bank.
The liability letter fixes the payoff figure, not the transfer
The liability letter gives the transaction a bank-issued payoff position for a limited period. DLD lists it as a required document for registering the sale of a mortgaged property, alongside the parties' identity evidence and the manager-cheque file. (DLD mortgaged-sale service, accessed 19 September 2026)
What appears on the letter depends on the lender and facility. HSBC UAE, for example, says a liability letter can cover a mortgage and includes outstanding balances, interest owed to date and interest over the next 15 days. Its mortgage-closing page describes the payoff amount as including charges and accrued interest. (HSBC liability-letter page, HSBC mortgage-closing page, both accessed 19 September 2026)
That makes the letter more than a balance screenshot. The recipient, issue date, expiry date, payoff amount, included charges, accrued interest treatment and payment instructions all matter. The current mortgage account balance can keep moving while the bank prepares the document, which is why the issued payoff figure and its dates belong together.
The full mortgaged-property sale workflow covers the wider transaction. This companion stays with the letter and the evidence it hands off to.
Four documents do four different jobs
The cleanest way to read the file is by issuer and effect. A document from one party does not perform another party's job.
DLD's property-sale page lists the developer e-NOC through Dubai REST for freehold areas and the electronic title deed as an output. Its mortgaged-sale page separately says completion follows submission of the bank's mortgage-release letter. (DLD property-sale registration, DLD mortgaged-sale service, accessed 19 September 2026)
Bank labels can add confusion. A lender may use terms such as clearance letter, no-liability letter or mortgage release in its customer journey. The useful test is functional: does the document quote what must be paid, or does it evidence that the mortgage can be removed after payment? DLD's published route requires both stages.
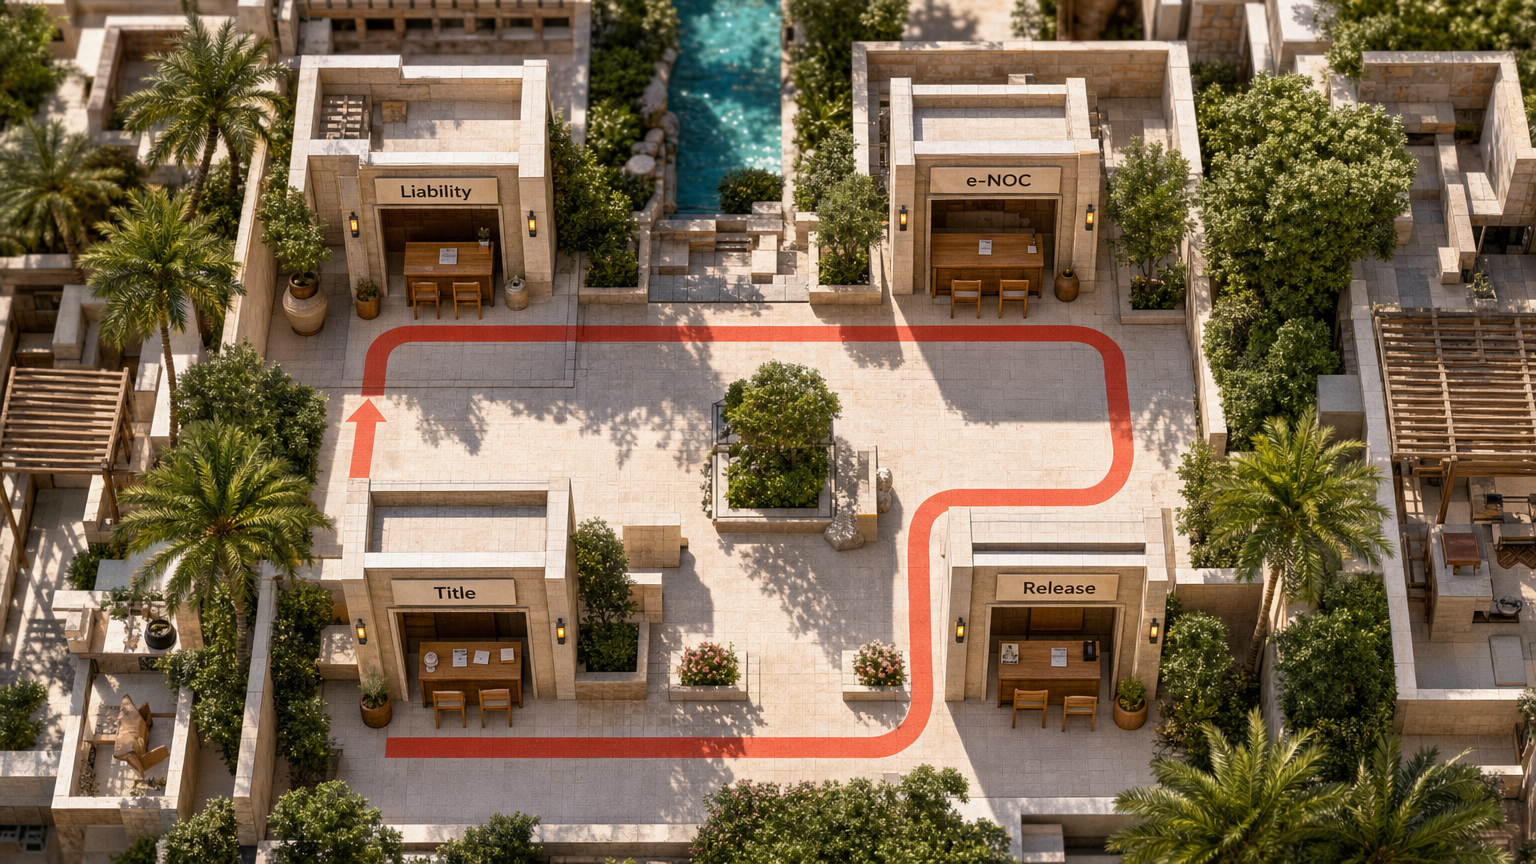
Who acts, and when
The sequence works when each party knows which handoff it owns. The table uses official DLD steps and named bank examples; it does not impose one lender's turnaround on another lender.
The DLD service time is not a promise that the banks, developer and seller will finish in the same sitting. DLD's own sequence has a bank-settlement handoff between initial registration and final completion. (DLD mortgaged-sale service, accessed 19 September 2026)
When the buyer also uses a mortgage, the buyer bank joins the chain. HSBC's published seller scenarios, for example, ask for the other bank's name and provide a liability-letter copy for that institution. That is one bank's process, but it shows why the addressee and delivery route need to be confirmed before the letter is ordered. (HSBC mortgage-closing page, accessed 19 September 2026)
What to confirm before requesting the letter
The useful pre-request checklist is a set of questions for the seller bank, buyer funding side and transaction file. It prevents a fresh letter from arriving before the other documents can use it.
- Correct product: confirm that the request is for the mortgage or home-finance facility attached to the property, not a general account-status letter.
- Correct addressee: confirm whether the letter must name the buyer's bank, buyer, trustee route or another recipient.
- Payoff contents: confirm whether principal, accrued interest, early-settlement charges and other facility charges are included, and how later interest is treated.
- Issue and expiry dates: read both dates on the issued document. Do not substitute a period quoted by another bank.
- Turnaround: ask when the bank starts its clock and what complete documents it needs. HSBC publishes 7 working days for its home-loan closing letter; Emirates NBD publishes 6 working days for its general liability letter. These are separate, bank-specific examples as of 19 September 2026.
- Fee and revalidation: confirm the request fee and what happens if the letter expires. Mashreq's current mortgage schedule, for example, lists AED 89.25 for a liability letter addressed to another bank and AED 525 for revalidation. Those figures belong to Mashreq's published schedule, not every lender.
- Settlement instrument: confirm the exact payee, amount and form the seller bank and trustee file will accept.
- Release path: confirm who collects or receives the post-payment bank evidence, whether an original is required and how it reaches the trustee for mortgage removal and sale completion.
- Parallel file: confirm the buyer funding stage and the developer e-NOC path. The vacant-versus-tenanted sale document guide explains the wider property file around that e-NOC.
Emirates NBD's current general liability-letter page says its letter is valid for 15 days. That does not create a 15-day Dubai rule, and the page is not limited to mortgage settlements. It is evidence that validity is an issuer term which must be read from the correct product and letter. (Emirates NBD, accessed 19 September 2026)
A worked dated sequence shows where the window matters
This example uses assumed dates to show coordination. None is a statutory deadline, a lender commitment or a prediction of completion.
21 September 2026: define the route
The seller confirms that the buyer is using a mortgage and records the buyer bank's exact name. The seller bank confirms what it needs to issue the mortgage-specific liability letter, how the letter will be addressed and how long its own process is expected to take.
22 September 2026: request the letter
The seller submits a complete request. Work on the buyer-bank file and developer e-NOC continues in parallel, because the useful window begins only when the bank issues the document.
28 September 2026: read the issued dates
Assume the bank issues the letter on this date and prints 12 October 2026 as its expiry. Those two dates are hypothetical. The transaction team copies the actual payoff amount, payee, reference and expiry from the issued letter rather than relying on an earlier balance.
29 September to 1 October 2026: align the other issuers
The buyer bank checks the letter against its funding conditions. The developer e-NOC is placed in the file. No claim is made that either issuer must complete within this illustrative interval; the example assumes they do.
5 October 2026: submit the trustee file
The parties use the live liability letter and the required instruments in the DLD mortgaged-sale route. DLD says the file includes a cheque for the bank or developer debt, a cheque for the seller's remainder if any and a cheque for the Department's 4% fee. (DLD mortgaged-sale service, accessed 19 September 2026)
8 October 2026: submit release evidence
After the seller bank's settlement and release process, the seller or buyer submits the mortgage-release letter. DLD then completes the mortgage release, sale and new mortgage procedure if there is one. In this hypothetical, the handoff remains inside the assumed expiry window.
The exact dates can change without changing the logic. The liability letter needs to remain current through the point at which the approved settlement file relies on its payoff figure. The seller bank and trustee can identify that point for the actual transaction.
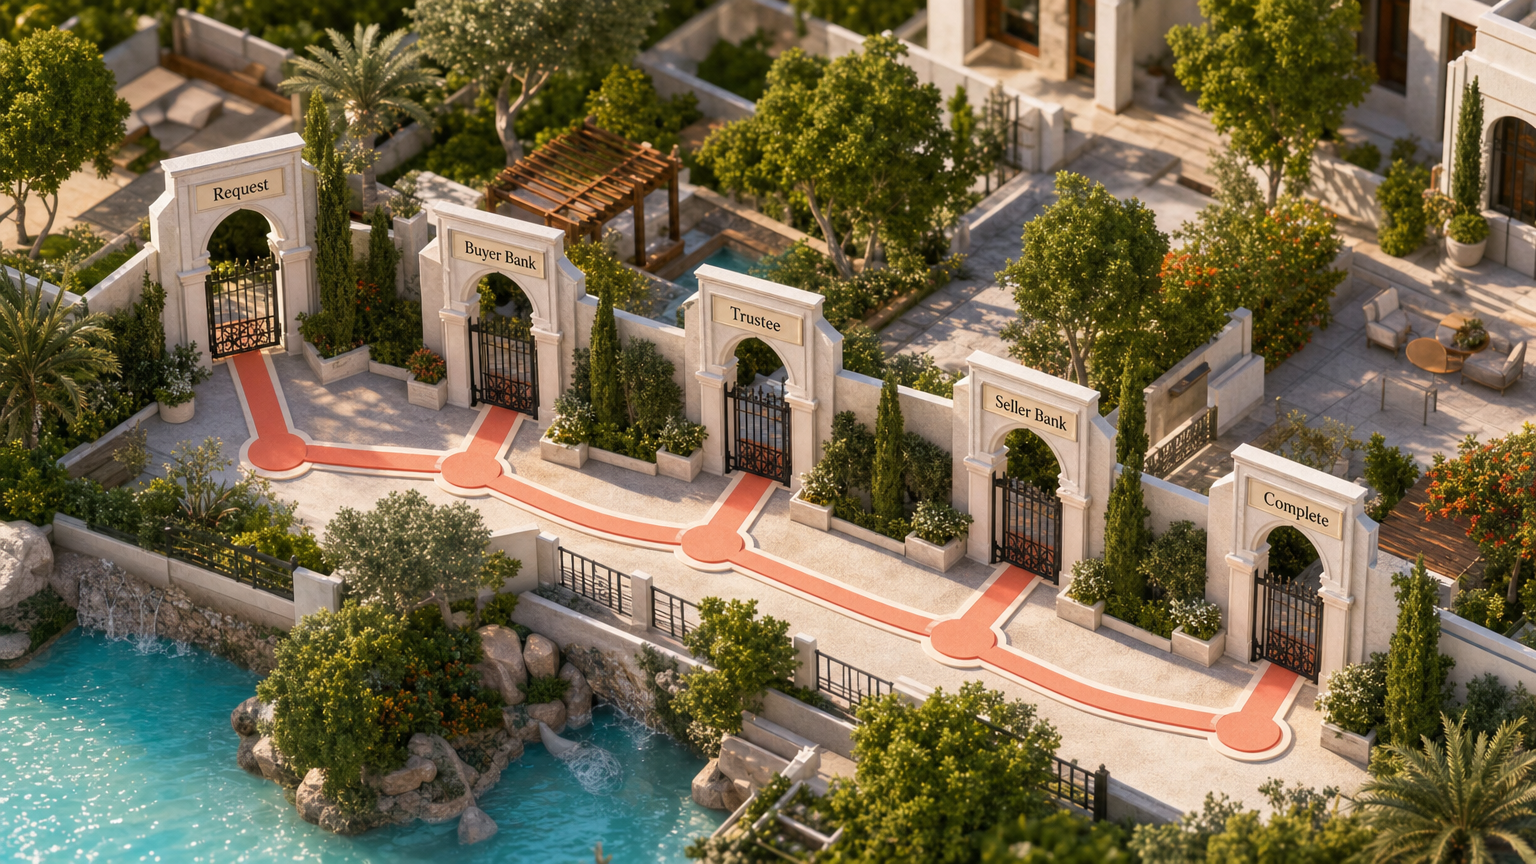
An expiry changes the quote, not the document roles
An expired letter no longer presents itself as the current bank payoff statement. Interest, charges or the facility balance may have changed, even if the property, price and parties are unchanged.
The next step is bank-specific. It may be a revalidation, a fresh request or another procedure under the facility terms. Mashreq's published mortgage schedule includes a revalidation fee, while Emirates NBD publishes a validity period for its general liability letter. Neither term can be assigned to another bank. (Mashreq schedule, Emirates NBD liability-letter page, accessed 19 September 2026)
Expiry also does not convert the developer e-NOC into bank evidence or cancel the need for the mortgage-release stage. It simply means the payoff document needs to return to the issuing bank's current process before the settlement file can rely on it again.
How long is a Dubai mortgage liability letter valid?
DLD's mortgaged-sale page does not publish one universal validity period. The issuing bank's document controls: as one bank-specific example, Emirates NBD says its general liability letter is valid for 15 days, but that page is not a Dubai-wide mortgage rule. (DLD, Emirates NBD, accessed 19 September 2026)
What information does a mortgage liability letter contain?
The exact fields vary by lender. HSBC UAE says its liability letter can include mortgage balances, interest owed to date and interest over the next 15 days; its mortgage page says the payoff amount includes charges and accrued interest. (HSBC liability letter, HSBC mortgage closing, accessed 19 September 2026)
Is a liability letter the same as a mortgage-release letter?
No. DLD requires the liability letter in the initial mortgaged-sale file and says the sale completes after the mortgage-release letter is submitted. The first states the payoff position; the second supports the post-settlement release stage. (DLD mortgaged-sale service, accessed 19 September 2026)
Is the developer e-NOC the bank's clearance?
No. DLD lists the developer e-NOC for a freehold sale-registration file, while its mortgage-release service requires bank evidence for mortgage removal. They come from different issuers and perform different jobs. (DLD sale registration, DLD mortgage release, accessed 19 September 2026)
What changes when the buyer also uses a mortgage?
The buyer bank becomes part of the payoff and new-mortgage coordination. HSBC's own process, for example, asks for the other bank's name and prepares a liability-letter copy for it; the actual seller and buyer banks set the transaction's documentary instructions. (HSBC mortgage closing, accessed 19 September 2026)
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.