Dubai resale completion-day payment map (2026)
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents+
As of September 2026, DLD's ordinary sale-registration schedule assigns 2% of the sale value to the seller and 2% to the buyer, while the official Contract F puts the balance consideration in a manager cheque payable to the seller. DLD's mortgaged-property sale service uses a different route with three manager cheques, so the two ledgers do not combine.
For the full path from appointment to title transfer, start with how to sell property in Dubai. This companion focuses only on the money and evidence at completion.
The ordinary resale starts with the signed payment allocation
The controlling payment map is the signed contract, not a generic list of seller costs. DLD's official Property Sales Contract, commonly called Contract F, records the sale price, deposit, balance payment and the parties' allocation of the 4% DLD transfer fee. It states that the buyer pays the balance by manager cheque in favour of the seller, unless another DLD-accepted payment method is used (DLD Contract F, accessed September 2026).
A manager cheque is a bank-issued payment instrument naming a specific payee. Its face amount is not automatically the seller's net proceeds. The seller may also have a deposit held in trust, a DLD fee share, a broker invoice and a developer clearance invoice elsewhere in the file. Those items have to be reconciled once, without counting the deposit twice or silently subtracting an invoice from the consideration cheque.
The deposit deserves its own line. Contract F says the security cheque is held in trust and describes when it may become a down payment after registration. The Form F clause map explains the contract dates and deposit mechanics in context.
The payment map has six separate checks
Each amount has its own preparer, recipient and source of truth. The trustee employee verifies the required documents, enters the transaction, audits it, collects the official fees and issues a receipt. The parties still reconcile private payment instruments and invoices against their contracts.
DLD requires a developer no-objection e-certificate, or e-NOC, for sales in freehold areas through Dubai REST. The current ordinary registration page does not publish one universal developer NOC fee. The transfer file therefore uses the actual developer invoice or clearance record, rather than an assumed market-wide amount (DLD Property Sale Registration, as of September 2026).
DLD's Contract A workflow also includes commission details for the owner-broker agreement. That makes the signed commission field and the brokerage's invoice the relevant evidence for the broker payment, not an uncited standard percentage (DLD Contract A workflow, accessed September 2026).
As of September 2026, DLD's Property Sale Registration schedule lists a 2% seller share, a 2% buyer share and a service-partner charge of AED 4,000 plus VAT when the sale value is at least AED 500,000.
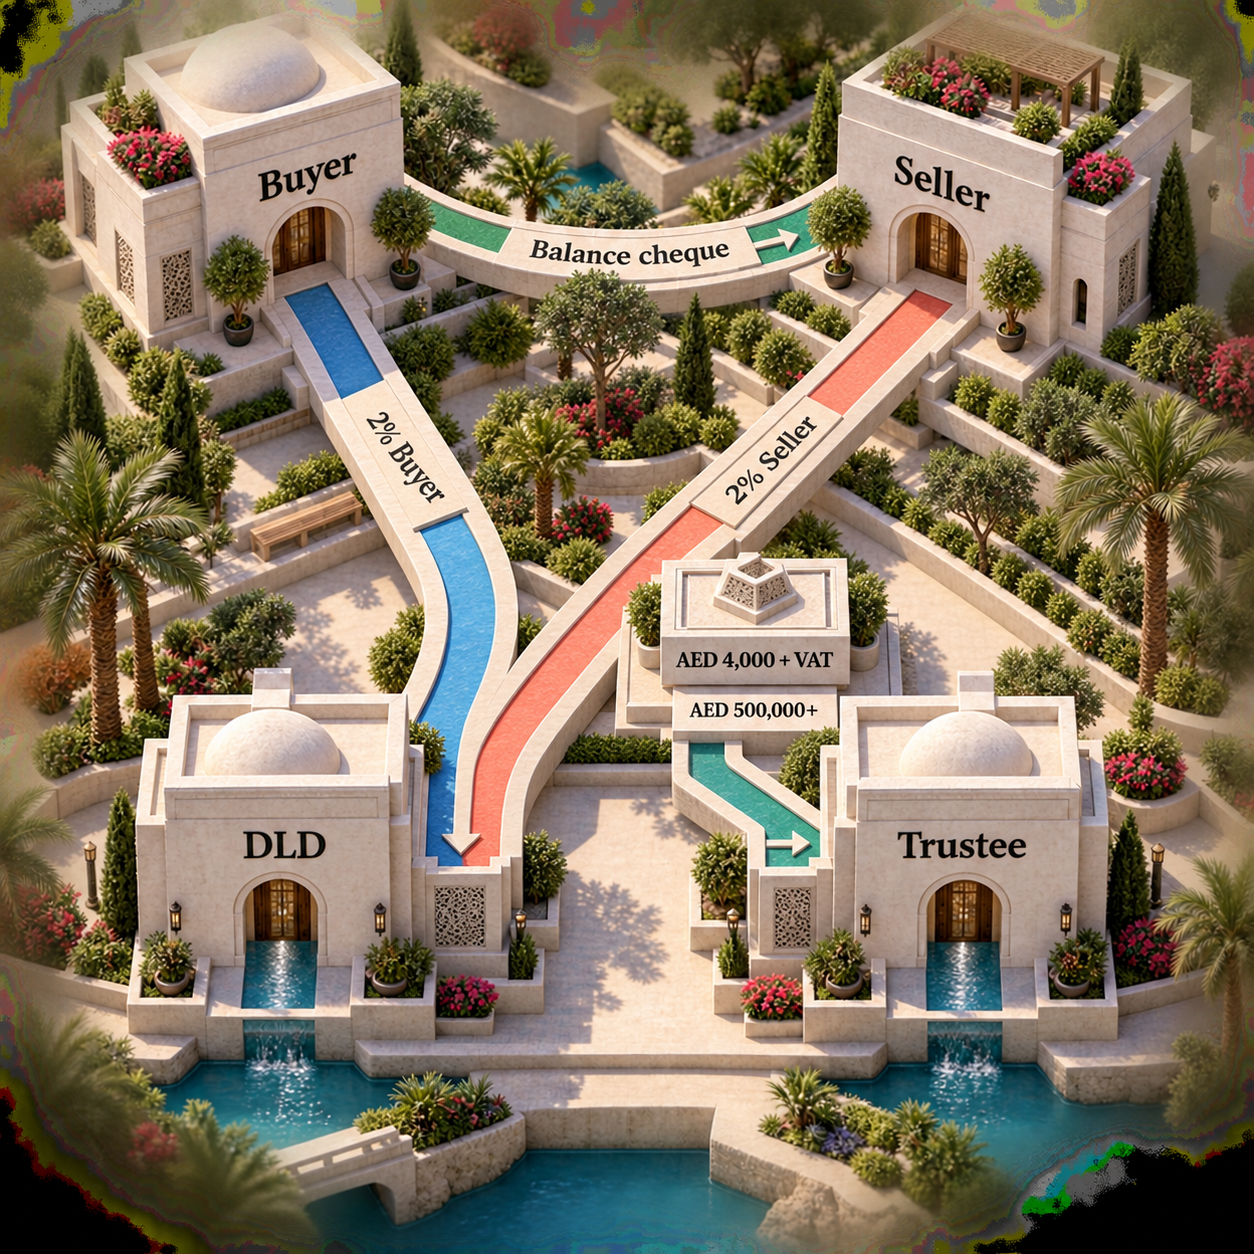
A worked AED 2 million ledger separates cash from net proceeds
The clean calculation starts with contractual inputs, then subtracts only seller-paid costs. This hypothetical is a teaching ledger, not a quote for a particular transfer.
The seller receives AED 2,000,000 of gross consideration in two pieces in this example: release of the AED 200,000 deposit as part-payment and the AED 1,800,000 manager cheque. The AED 1,916,500 net is a reconciliation after the listed seller costs. It is not the required face value of one manager cheque.
The buyer's DLD share is separately AED 40,000 in this example. Because the sale value is at least AED 500,000, DLD lists the ordinary service-partner fee at AED 4,000 plus VAT. This worked file assumes the buyer pays that charge, plus the title deed and map outputs, because its completion statement says so. The actual signed allocation and fee balance remain controlling (DLD, as of September 2026).
A mortgaged sale uses a separate three-cheque route
An active seller mortgage changes the route before it changes the arithmetic. DLD's dedicated service requires a bank liability letter, or a developer letter showing the remaining amount, plus three manager cheques: one to the bank or developer for the debt, one to the seller for any remainder and one to DLD for the 4% sale fee (DLD Registering the Sale of a Mortgaged Property, as of September 2026).
The liability letter is the bank's dated statement of the amount needed to settle the home loan. It is the input for the debt cheque. DLD says its auditor issues a registration certificate and the indebtedness cheque is delivered so the seller can complete the bank process. Final mortgage release, sale and any new mortgage procedure follow submission of the mortgage release letter.
That sequence is why an ordinary sale ledger cannot simply deduct an estimated loan balance from the seller cheque. The special route names the bank as a payee and makes the release letter a condition of final completion. The mortgage liability letter guide covers the request and validity sequence.
The current CBUAE retail fee appendix caps a home-loan early-settlement fee at 1% of the outstanding balance or AED 10,000, whichever is less. It also caps a home-loan liability letter at AED 85 and a clearance letter at AED 95. These are maximums, not a bank quote, so the current liability letter remains the amount used in the completion file (CBUAE Consumer Protection Standards, accessed September 2026).
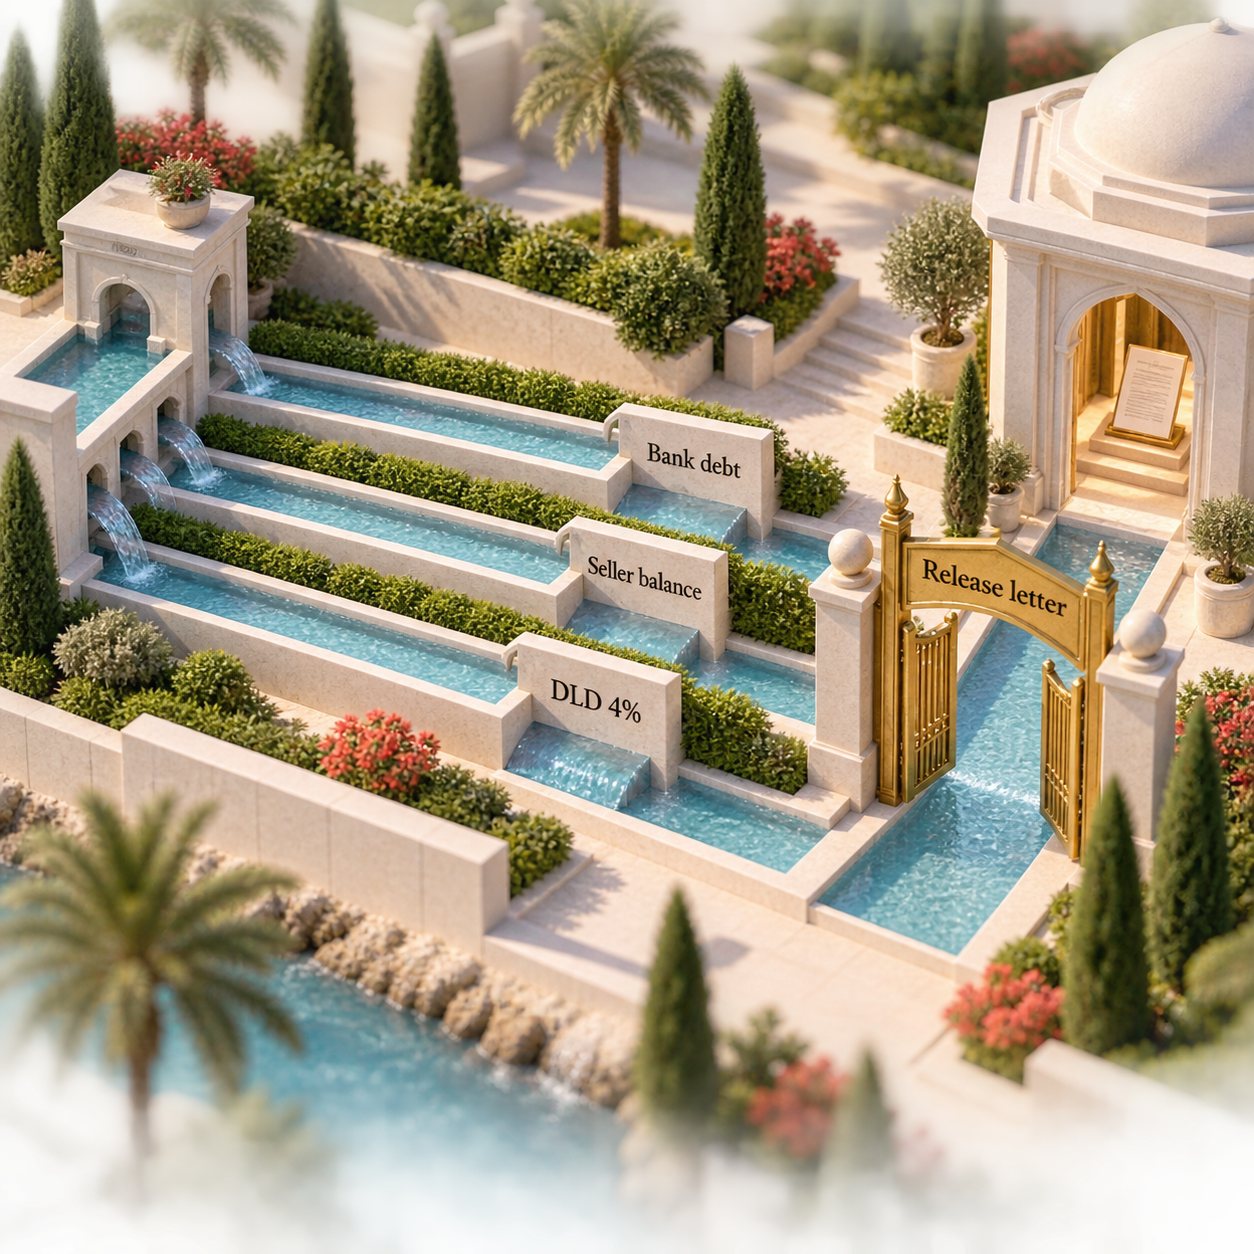
The trustee-office sequence turns the ledger into receipts
The day moves from document verification to audit, payment and electronic outputs. DLD gives an ordinary property-sale service time of 25 minutes, but that is the published service time, not a promise for the full appointment or the preceding bank and developer work (DLD, as of September 2026).
Freeze the completion statement
The file records the sale price, deposit treatment, balance cheque, each DLD fee share, trustee charge, broker invoice and any developer invoice. Every payee name matches its supporting document.
Present identity and transfer evidence
The parties or their authorised representatives present the required identification. For a freehold-area sale, the file includes the developer e-NOC. The trustee employee identifies deficiencies before the transaction is entered.
Enter and audit the transaction
The trustee employee enters the transaction data and performs the audit described on DLD's service page. This is the point to distinguish official fee verification from the parties' reconciliation of private invoices.
Pay official fees and collect receipts
DLD lists ePay, Dubai Pay, Noqodi Wallet and manager cheque as payment methods for the ordinary service. The fee receipt is evidence of what was paid to the official route.
Receive the electronic outputs
DLD issues the electronic title deed and map by email. The seller's completion file retains the final statement, cheque copy or bank evidence, e-NOC, invoices and official receipts.
The seller's net is proved by the full file
The reliable net figure is gross consideration minus seller-paid items, with every deposit and debt payment counted once. A cheque photocopy alone cannot show that calculation because some costs may have been paid earlier, some may be settled separately and a mortgage debt cheque may go directly to the lender.
The final evidence pack therefore connects five records: the signed Contract F, the deposit status, the named manager cheque or bank payment, the official DLD and trustee receipts, and the private invoices or bank settlement evidence. Reproducing the stated seller net from those records leaves no unexplained balancing line.
Who pays the 4% DLD transfer fee in a Dubai resale?
As of September 2026, DLD's ordinary sale-registration page lists 2% of the sale value for the seller and 2% for the buyer. The official Contract F also records the parties' fee allocation, so the signed contract and DLD fee balance show the amounts for the particular transfer.
Is the manager cheque made out to DLD or to the seller?
For an ordinary resale, the official Contract F says the balance manager cheque is in favour of the seller, unless another DLD-accepted method is used. Official DLD fees are separate. In the special mortgaged-property route, DLD requires distinct cheques for the debt recipient, the seller remainder and DLD's 4%, as of September 2026.
Can a mortgaged Dubai sale complete before the mortgage release letter?
DLD's special mortgaged-property service says the final sale procedure is completed after the mortgage release letter is submitted. The debt payment and registration certificate come earlier in that route, as of September 2026.
Does the trustee office verify the broker invoice?
DLD's ordinary service procedure describes verification of required documents, transaction entry, audit, official fee payment and receipts. It does not say the trustee certifies a private broker invoice. As of September 2026, that invoice is reconciled against the agreed commission details and the brokerage's own invoice and receipt.
Does the developer NOC fee come out of the seller's manager cheque?
Not automatically. DLD requires the e-NOC for a freehold-area sale, but its ordinary registration page does not set one universal developer NOC fee. As of September 2026, the actual developer invoice, its payment status and the signed completion statement determine whether any amount remains to be paid.
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.