Off-plan mortgage Dubai: LTV, approval and drawdown (2026)
 Lida Moghaddam
Disclaimer: This article is for general informational purposes only. It is based on cited public data and published under Lida Moghaddam's RERA-licensed masthead. It is not financial, legal, or investment advice. Dubai's property market moves quickly, so figures, yields, and rules may change or become outdated by the time you read this. Verify current information with the relevant authority or a qualified professional before acting. Read the full disclaimer.
Table of contents
An off-plan home in Dubai can be financed, subject to lender approval. The Central Bank of the UAE (CBUAE) sets a 50% maximum loan-to-value ratio, regardless of purchaser category, purpose or value, as of 21 October 2026. That is a ceiling, not a bank offer. Developer instalments, mortgage pre-approval and actual funds released establish different things. Source: CBUAE Article 3.
Source: withlida.com, 21 October 2026, from CBUAE's mortgage regulations, as accessed that date, and Emirates NBD's announcement dated 16 April 2026.
The non-resident mortgage guide covers the wider overseas borrower route. This page follows bank financing while the property is still under construction.
Last verified: 21 October 2026. Checked by the publication's independent check, 21 October 2026.
Can an off-plan home in Dubai be mortgaged?
Yes, the CBUAE framework expressly provides for mortgages on property purchased off plans, meaning a purchase before construction is complete. Its off-plan category sets a lending limit; it does not require a bank to finance a particular home or applicant. The regulations also permit lenders to apply more conservative limits. CBUAE mortgage regulations, as of 21 October 2026.
A developer payment plan spreads the purchase-price obligations under the sale and purchase agreement, or SPA. It records what the buyer owes the developer and when. A bank mortgage is a separate credit arrangement, with borrower assessment, collateral and release conditions. Paying a reservation amount or meeting a developer instalment does not, by itself, create that credit arrangement.
This distinction matters when a schedule contains a substantial later payment. The signed schedule establishes the payment obligation. A separate bank file establishes whether financing can meet it. Treating a future mortgage as the payment source requires evidence of both the sanctioned amount and the conditions governing its availability at that event.
There is a dated product example. On 16 April 2026, Dubai Holding Real Estate and Emirates NBD announced a memorandum of understanding for integrated off-plan mortgage financing across Meraas, Nakheel and Dubai Properties. The release describes tailored solutions from the initial stages of the purchase and mortgage pre-approval during the off-plan stage. It says the initiative is available to eligible UAE residents and non-residents, subject to approval. Emirates NBD, announcement read 21 October 2026.
The release does not specify a universal construction-completion threshold, a personal facility amount or the date funds become payable for an individual purchase. Its April publication date also remains the event date when read in October. For an existing purchaser, the relevant unanswered question is whether the bank accepts that particular contract, project and current payment stage under its current terms.
What is the regulatory LTV ceiling for an off-plan mortgage?
The maximum is 50%, regardless of the purpose, value or purchaser category, under CBUAE Article 3's off-plan provision, as of 21 October 2026. Loan-to-value, or LTV, means the outstanding loan divided by the property's appraised value under Article 1. It is a collateral ratio, not the share of your developer instalments already paid. CBUAE Articles 1 and 3.
The facility can be smaller because the lender must also assess repayment capacity and its own lending criteria. Article 2 expressly says the published LTV ratios are maximum allowable levels and that lending decisions must not rely on collateral instead of assessing affordability. A valuation within the regulatory limit therefore answers only part of the financing question. CBUAE Article 2, as of 21 October 2026.
Other regulatory limits apply alongside LTV rather than replacing it:
Source: withlida.com, 21 October 2026, from CBUAE Article 3, as accessed that date. The income categories above reproduce the regulation's categories; they do not create a separate non-resident product entitlement.
For someone with a payment schedule, the practical distinction is between a regulatory calculation and an actual sanctioned facility. The former describes the permissible boundary. The latter records what this lender has approved for this borrower and property, with its conditions. Neither a purchase-price percentage in a brochure nor a pre-approval estimate substitutes for the latter document.
Can residents and non-residents apply for construction-stage financing?
Both groups are within the eligibility described in the 16 April 2026 Emirates NBD partnership announcement, subject to approval. That statement supports an application route for eligible applicants. It does not establish that every resident, overseas income source or project is accepted. Emirates NBD, accessed 21 October 2026.
Residence status, nationality and income evidence answer different questions. An applicant living abroad still needs the lender's own confirmation of the applicable borrower category, acceptable income evidence and project scope. An applicant living in the UAE also needs an individual assessment. The off-plan regulatory LTV ceiling remains the ceiling across purchaser categories; application eligibility does not increase it.
CBUAE Article 2 requires lenders to verify income and liabilities and assess reliable, sustainable repayment capacity. It identifies other debt, household commitments and employment circumstances as relevant factors. A developer payment history helps reconcile the purchase account, while the bank's income file serves the separate task of assessing the borrower. CBUAE Article 2, as of 21 October 2026.
The best-fit documentation path follows the income source. A salaried file centres on employment and salary evidence. A business-owner file centres on the records supporting business income. An overseas file additionally needs the bank's written list for the applicant's country and circumstances. These are file categories to clarify with the lender, rather than a single checklist imposed on every applicant.
The same separation applies to timing. Eligibility to apply now is not evidence that a loan can pay the next developer demand. The application file and the payment schedule need to be read together, with each payment matched to the release condition that could fund it.
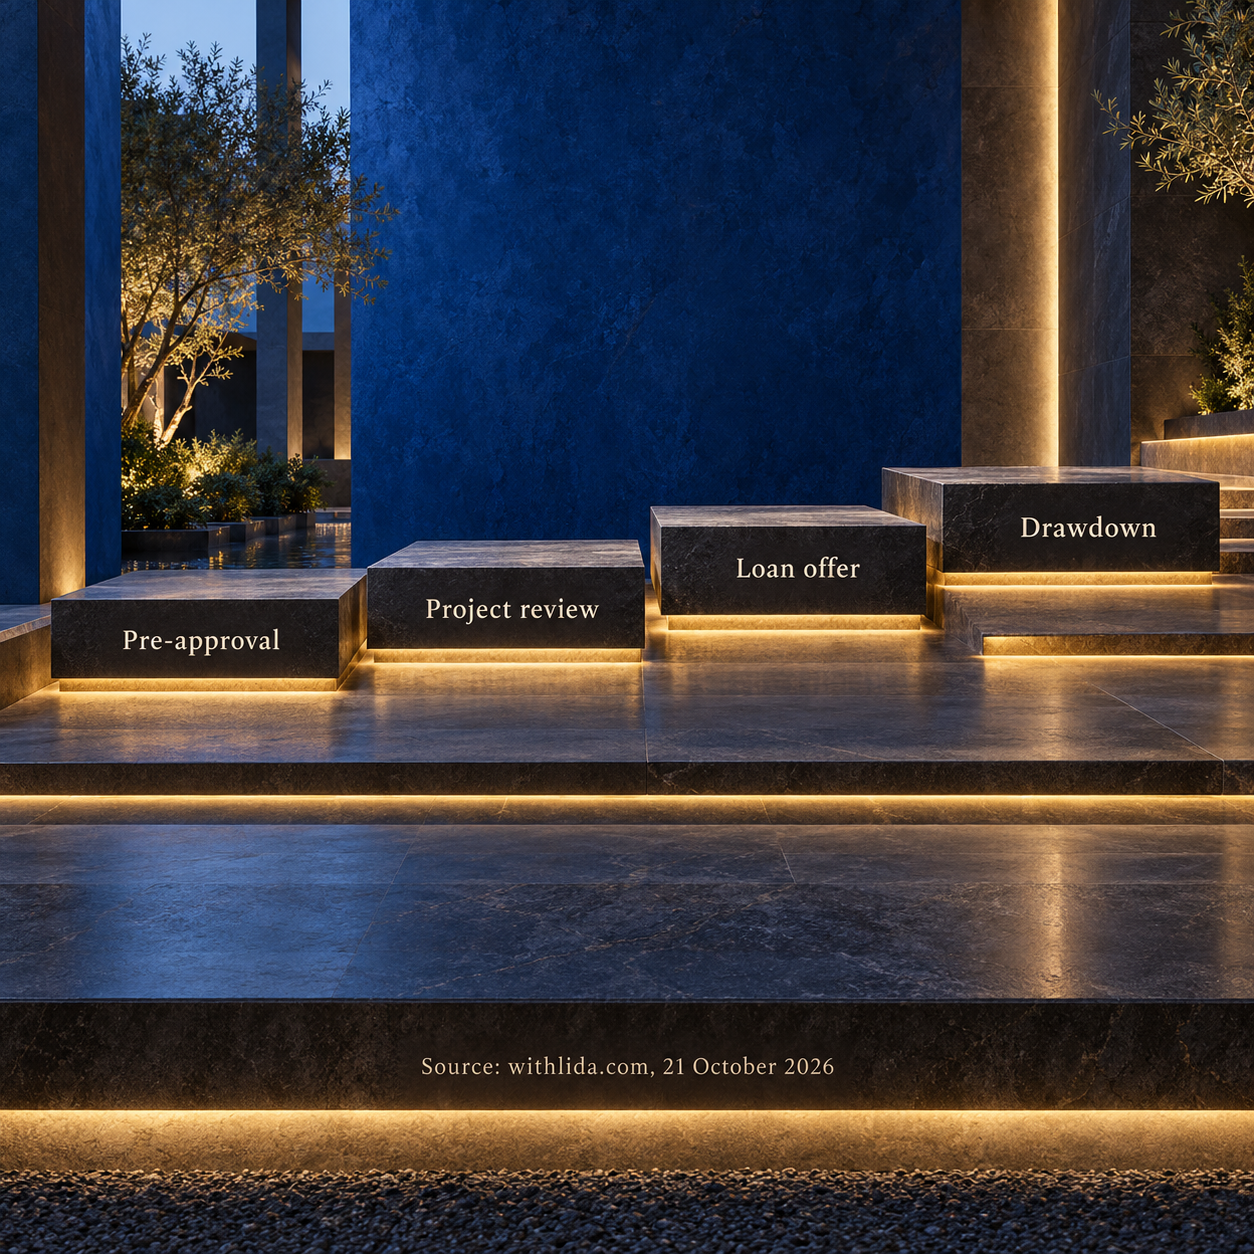
Is mortgage pre-approval the same as money available to pay the developer?
No. Pre-approval is an initial assessment of possible borrowing; drawdown is the release of loan funds under the financing arrangement. For example, HSBC describes approval in principle as showing what it may be able to lend, followed by a full mortgage application. That is a general process illustration, not evidence that HSBC participates in the April off-plan partnership. HSBC application guide, as of 21 October 2026.
The following table is an evidence map. Some checks may overlap; the names do not prescribe one universal bank workflow.
Source: withlida.com, 21 October 2026. Analytical distinctions based on CBUAE Articles 2 and 4, HSBC's application stages, and the Emirates NBD April announcement, all read that date. Contract-specific events require their own signed records.
A useful file entry records the issuer, property or project reference, approved amount, outstanding conditions and any validity date stated in the document. A later record can then be compared with the earlier one without assuming they have the same scope. A pre-approval attached to the borrower may leave the development unspecified; a project confirmation may leave the borrower assessment outstanding.
CBUAE Article 2 requires an independent on-site valuation before an irrevocable lending commitment and procedures to check compliance with loan conditions before drawdown. Article 4 requires the loan documents to specify disbursement and progress-payment milestones. Those requirements explain why an approval letter and a released payment remain distinct. CBUAE regulations, as of 21 October 2026.
When can off-plan mortgage funds be released?
For construction stage payments, the bank must first use the owner's equity portion and base payments on prescribed, physically verified completion milestones. CBUAE Article 2 states these requirements as of 21 October 2026; the cited provision does not set one completion percentage for every development. CBUAE Article 2.
The buyer's paid proportion, the project's construction progress and the bank's release conditions are separate measures. A payment receipt proves money paid. A progress confirmation addresses construction. The financing agreement identifies how those records connect to a permitted advance. Reaching a particular paid proportion does not alone establish that all the other conditions are satisfied.
Article 4 requires loan documentation to identify the mode and method of disbursement and the milestones for progress payments on properties under construction. The transaction-specific answer therefore belongs in the financing documents: what payment can be funded, the required evidence, the payee and the release process. CBUAE Article 4, as of 21 October 2026.
Match the next demand to the contract
The working entry records the SPA payment event, amount, due trigger and developer statement of account. It distinguishes a date-based demand from a milestone-based obligation according to the signed wording.
Match the payment to the financing terms
The bank's record identifies whether that demand falls within the sanctioned facility, what equity must already be used and which completion evidence is required. A remaining facility balance alone does not answer these questions.
Record the release confirmation
The payment record identifies the amount and recipient actually paid. Until a release is evidenced, the cash schedule can show it as conditional rather than as money already received or credited.
This working sequence is an editorial reconciliation method, not an additional regulatory timetable. It keeps the contractual payment obligation visible while the bank completes its own checks.
Handover also needs its own entry. A payment due at handover does not, solely because of that label, establish the bank's lending classification or automatic release. The relevant facility, property status and security arrangements require current lender confirmation. The Dubai buying-process guide follows the broader purchase and registration route.
What cash remains necessary? A symbolic payment ledger
The buyer's remaining price contribution is the unpaid contract price minus bank money actually applied to those remaining payments, with separately evidenced unpaid fees added. The calculation uses the actual sanctioned facility and releases, rather than assuming the regulatory ceiling becomes the loan.
Freeze the example at a point before any bank drawdown. All instalments already credited in this example came from the buyer. The symbols are worksheet inputs, not a reported transaction, property price or forecast of approval.
Source: withlida.com, 21 October 2026. Original symbolic ledger using the CBUAE LTV definition and off-plan ceiling, as of that date. The lender may use a more restrictive valuation basis or approve less after underwriting.
The completed ledger reads:
- Additional buyer cash toward the price = R − B.
- Total buyer cash toward the price = I + R − B = C − B.
- Additional buyer acquisition cash = R − B + F.
These identities assume the bank payments counted in B settle the same remaining price recorded in R. Earlier price credits are already in I, so they are not deducted again. Already-paid fees are excluded from F. This is an acquisition cash reconciliation, not the lifetime cost of borrowing; future loan repayments and financing charges need their separate repayment schedule.
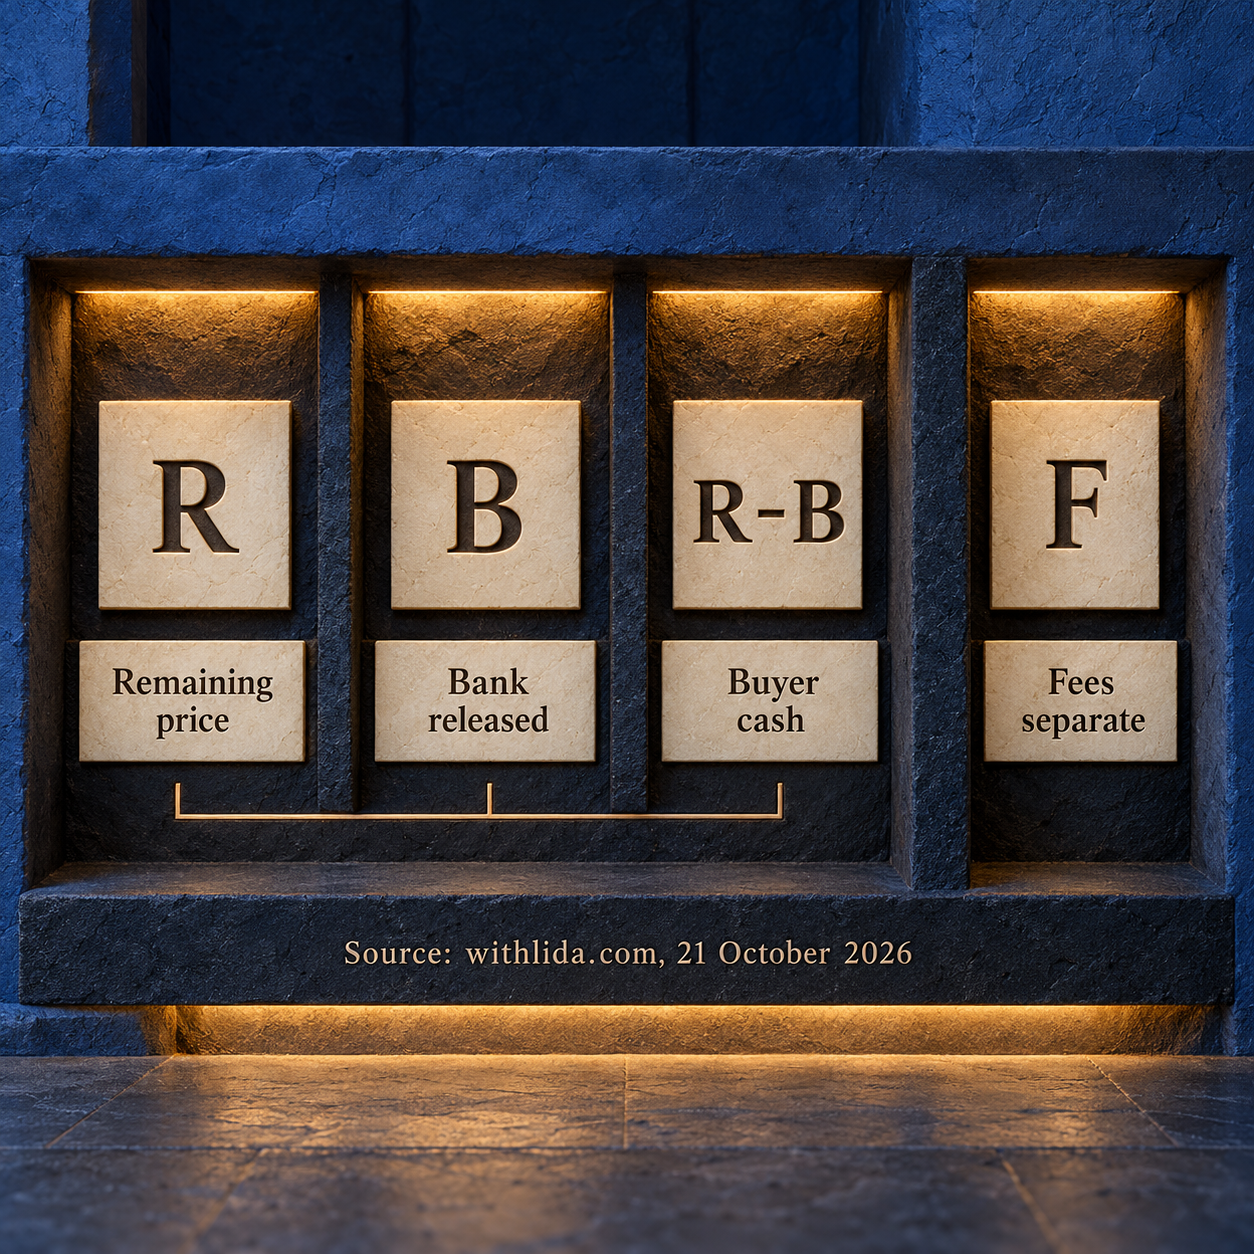
The timing calculation is just as important. For each future payment event, let A be the price amount due, D the bank funds released for that event and F-event the separately evidenced fee cash due then. Buyer cash at that event is A − D + F-event, with D no greater than A in this example. Across the remaining schedule, the A amounts total R and the D amounts total B.
If the release for an event has not occurred, D is zero in the actual-payment ledger. The full price demand remains visible, plus applicable fees, even if the offer contains unused borrowing capacity. A separate conditional column can show the proposed release without treating it as settled cash.
Nor does paying earlier instalments establish a right to have them reimbursed. This example assumes no reimbursement and no financed fees. Whether a particular facility allows either belongs in its express terms. The same is true of any unused sanctioned balance after a release.
Fees remain itemised rather than estimated as a blanket percentage. The evidence file can include applicable purchase registration charges, bank processing and valuation charges, insurance, security-registration costs, developer administration charges and any agreed agency charge. Each entry needs its current source, payer, due event, tax treatment and paid status. No tariff is implied by this list. CBUAE Article 4 requires a separate fee schedule attached to the loan contract. CBUAE, as of 21 October 2026.
Lida's practice: a direct off-plan purchase from a developer usually carries no buyer commission. Confirm it in the contract and with the developer; any agency agreement remains a separate record to check. This is her confirmed practice, recorded 21 September 2026, not a published tariff or an assumption that every fee is included in the price.
What documents remain necessary for the bank and the off-plan purchase?
The necessary evidence falls into borrower documents, purchase and payment records, and the bank's financing and release file. CBUAE requires income verification, collateral assessment and checks before drawdown; it does not replace those tasks with the developer's record of payments. CBUAE Article 2, as of 21 October 2026.
The borrower file supplies identity, income, liabilities and the source of the buyer contribution. Emirates NBD's general home-loan support page lists passport, residence documents, salary evidence, bank statements and address evidence, with business records for self-employed applicants and additional documents where requested. This is general home-loan context, not a complete non-resident or construction-stage product checklist. The lender supplies the list applicable to the actual application. Emirates NBD, accessed 21 October 2026.
The purchase file ties the applicant to the specific contract and account: signed SPA, payment schedule, receipts, statement of account and applicable provisional-registration evidence. Oqood is DLD's portal for provisional registration of off-plan sales. DLD's initial-sale service describes developer registration of off-plan units and issues a provisional registration e-certificate. Its individual-buyer documents include the signed sale contract and identity evidence, with a passport route for non-residents. Dubai Land Department, as of 21 October 2026.
A provisional-registration certificate establishes a registration fact. It does not establish a mortgage approval or a released bank payment. The off-plan records guide explains how purchase, payment and provisional-registration records align.
The financing and release file contains the property-specific acceptance, accepted valuation, sanctioned offer, contribution evidence and records satisfying the release conditions. CBUAE Article 4 requires the loan documentation to cover the development, borrower contribution, amount, repayment terms, insurance, disbursement and progress milestones. CBUAE, as of 21 October 2026.
The strongest fit for a buyer managing instalments is a file that answers the next payment question precisely: what is due, what buyer cash remains, what the bank has approved, what conditions remain and what has actually been paid. It leaves the financing decision with the reader while making the evidence behind each cash entry visible.
Off-plan mortgage FAQ, verified 21 October 2026
These answers distinguish the current regulatory ceiling from the terms of an individual financing file.
What does off-plan property mean in Dubai?
It is a property purchased before construction is complete. DLD's initial-sale service provides for provisional registration of units sold off-plan; that registration is separate from the bank's financing decision. DLD, as of 21 October 2026.
Can I get an off-plan mortgage as a non-resident?
Emirates NBD's 16 April 2026 partnership announcement includes eligible non-residents, subject to approval. It does not establish acceptance for every overseas applicant or project. Announcement accessed 21 October 2026.
Does the 50% LTV ceiling mean the bank will lend that amount?
No. It is the maximum off-plan ratio in CBUAE Article 3. Article 2 permits more conservative lender limits and requires repayment-capacity assessment. CBUAE, as of 21 October 2026.
Does pre-approval mean I can stop funding developer instalments?
Pre-approval alone does not establish funds released for an instalment. The payment obligation and the bank's disbursement conditions need separate evidence. CBUAE Article 4, as of 21 October 2026.
Must every project reach the same completion percentage before drawdown?
The cited CBUAE provision requires equity first and physically verified completion milestones for construction stage payments. It does not prescribe a universal completion percentage. The financing documents identify the applicable milestones. CBUAE Article 2, as of 21 October 2026.
Can the down payment come from a personal loan or credit card?
CBUAE Article 2 states that the borrower contribution must come from the borrower's own resources, rather than other borrowing including personal loans or credit cards. CBUAE, as of 21 October 2026.
What is the current interest rate for an off-plan home loan?
This guide quotes no current product rate. The April partnership announcement does not state an individual borrowing rate; pricing and its calculation belong in the lender's current disclosure and loan documents. CBUAE Article 4, as of 21 October 2026.
Change log: 21 October 2026 · first published · CBUAE mortgage provisions verified; the partnership retained its 16 April 2026 announcement date.
Subscribe to withlida's market brief for dated Dubai property rules and process explainers.
Lida MoghaddamArchitect-turned-real-estate-specialist based in Dubai. She helps buyers, sellers, and investors read property with a designer's eye — structure, location, and long-term value.